Bundled Auto Home Kitsap: Save More With Local Bundles
Bundling your auto and home insurance in Kitsap County isn’t just convenient-it’s one of the smartest financial moves you can make. Most people don’t realize how much they’re leaving on the table by keeping policies separate.
We at H&K Insurance Agency have helped hundreds of local families cut their premiums significantly through bundled coverage. The savings add up fast, and the protection gets better.
What Real Savings Look Like When You Bundle
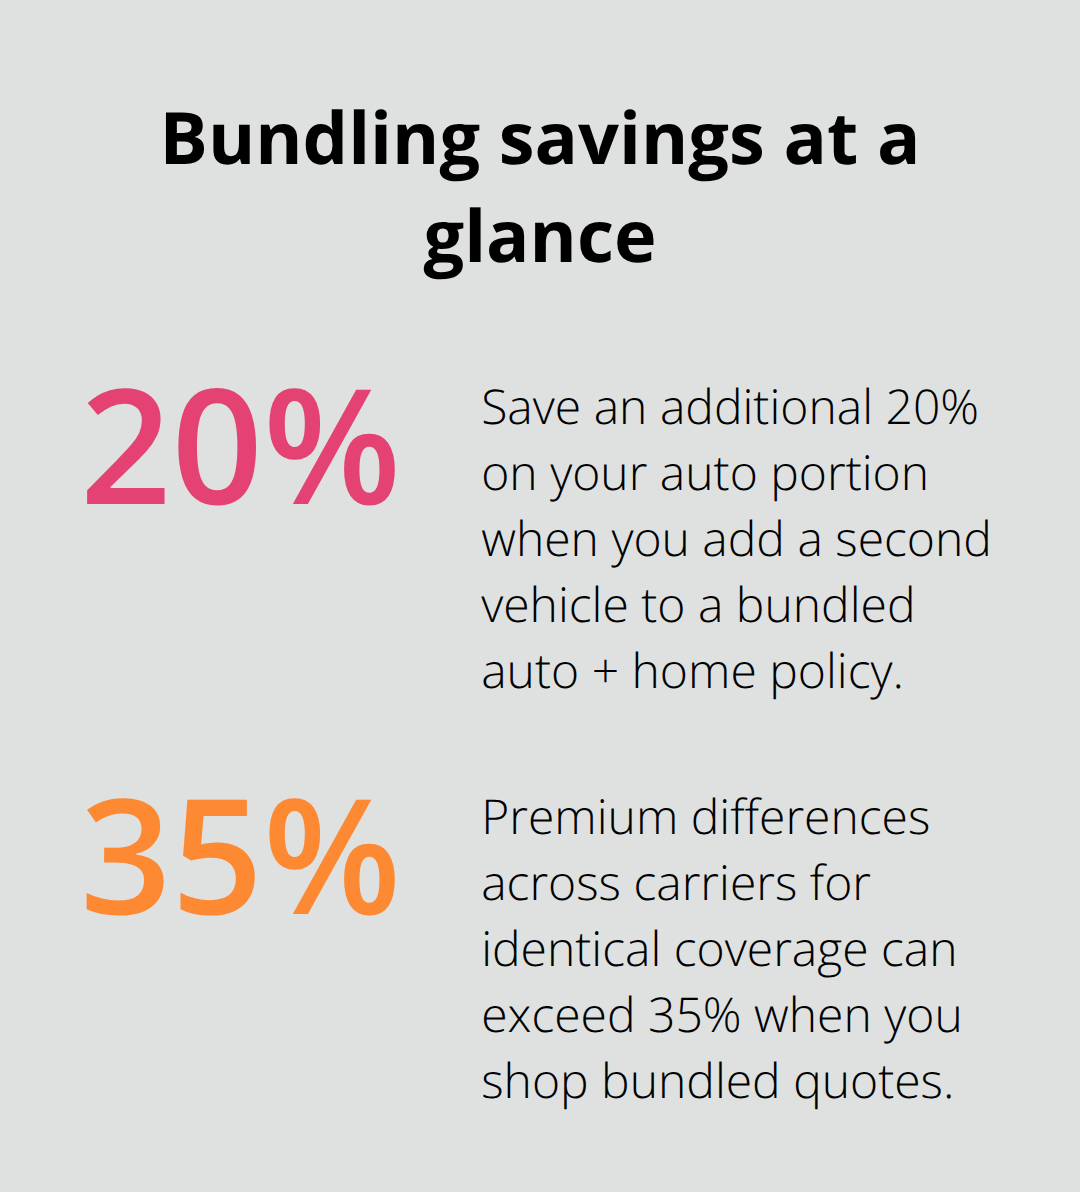
Bundling auto and home insurance in Kitsap County delivers measurable financial results. A 2025 State Farm survey of new policyholders who switched to bundled coverage reported average savings of up to $1,273 per household annually. That money stays in your bank account instead of going to insurance companies. When you add a second vehicle to an auto policy bundled with home coverage, you can save an additional 20% on your auto portion. Kitsap County residents who work with local independent agents often discover that premium differences across carriers for identical coverage exceed 35%-which means shopping bundled quotes properly can yield hundreds more in annual savings than accepting the first offer.
The real advantage appears when you compare what you actually pay versus keeping policies separated. Most people assume bundling saves 10-15%, but competitive local shopping typically reveals 15-25% reductions on your total premium when combining home and auto coverage.
How Insurance Companies Pass Savings to You
Insurance companies offer bundling discounts because managing one customer across multiple policies costs them less than maintaining separate accounts. That savings transfers directly to you. Beyond the base discount, bundling often unlocks additional discounts that don’t apply to standalone policies. If you raise your home deductible from $1,000 to $2,500 while bundling, you can save 8-15% on that portion alone-though you need liquid cash reserves to cover the higher out-of-pocket expense after a claim.
Specialized Coverage That Costs Less When Bundled
Water backup coverage protects against sewer backups and sump pump failures affecting roughly 10% of homeowners annually. This coverage costs only a few dollars monthly when bundled but carries higher premiums if purchased separately. Earthquake and flood endorsements, essential in Kitsap given the Cascadia Subduction Zone risk and floodplain exposure affecting over 175,000 structures in Washington, can reduce premiums by 10-20% when bundled rather than added separately. The single deductible feature available on some bundled policies simplifies claims management-if both your car and home suffer damage in the same event, you pay one deductible instead of two, which can save $500-$1,500 per incident.
Why Three Quotes Matter More Than Brand Loyalty
Obtaining quotes from three different carriers using identical property details and coverage specifications is non-negotiable. Premium variations for the same dwelling limit, liability coverage, and replacement cost value coverage regularly exceed 35% between carriers. One insurer might quote $1,200 annually while another charges $1,620 for identical protection-that $420 annual difference compounds to thousands over five years. When you evaluate bundled quotes, verify that each includes replacement cost value for both structure and personal property, at least $500,000 liability per occurrence, and 12 months of lost rental income coverage if you rent out any portion of your property. Many carriers exclude water backup, flood, and earthquake coverage by default, so bundled quotes that omit these endorsements aren’t truly comparable to those that include them.
Local Agents Simplify the Shopping Process
Independent agents in Kitsap can access multiple carriers simultaneously and explain exactly what each policy covers before you sign. This approach saves time and prevents the coverage gaps that solo shopping often creates. H&K Insurance Agency represents multiple top local and national carriers, which means you get customized packages that address Pacific Northwest risks without wasting hours on comparison calls yourself. The next step involves understanding which regional hazards matter most for your specific property and situation.
Why Kitsap Residents Need Local Bundling
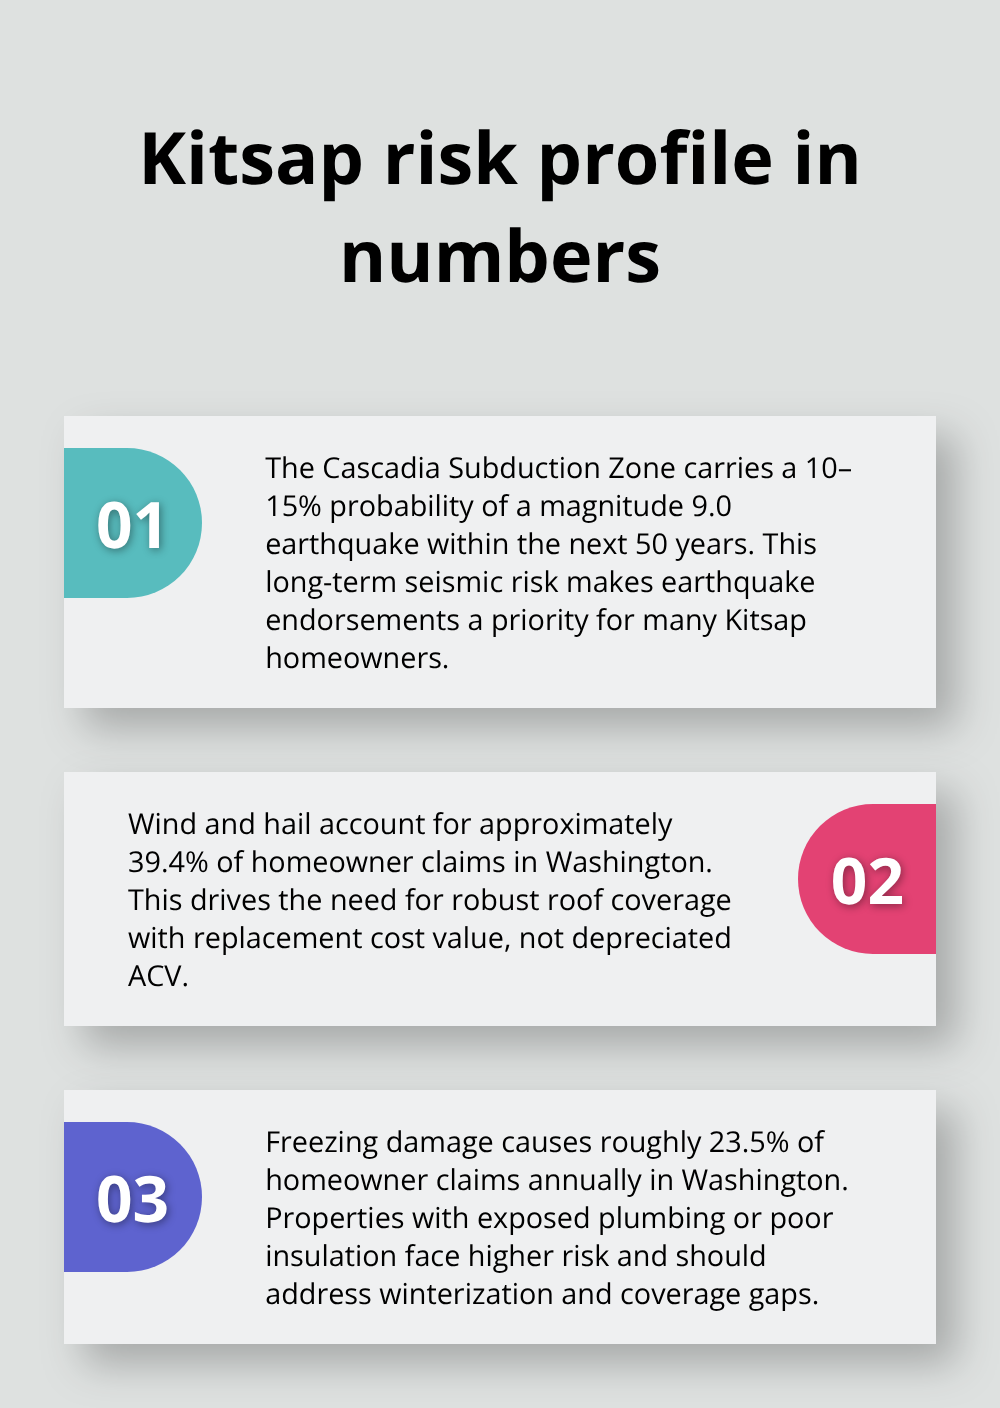
Kitsap County sits in one of America’s most geographically complex insurance zones. The Cascadia Subduction Zone presents a 10–15% probability of a magnitude 9.0 earthquake within the next 50 years, while more than 175,000 structures across Washington occupy designated floodplains. Wind and hail account for approximately 39.4% of homeowner claims in Washington, and freezing damage causes roughly 23.5% of claims annually.
Standard homeowners policies exclude both earthquake and flood coverage entirely, which means a bundled package from a national carrier with boilerplate terms leaves your property dangerously exposed. When you bundle through a local agent who understands Kitsap’s specific exposure profile, you access endorsements that address these exact risks. Earthquake coverage typically costs $200–$400 per year and protects structural damage, personal property, and additional living expenses. Flood insurance through the National Flood Insurance Program averages $400–$800 annually depending on elevation and foundation type. Adding these endorsements to a bundled policy reduces premiums by 10–20% compared to purchasing them separately, but only if your agent structures the package correctly from the start.
Localized Risk Assessment Changes Your Coverage Needs
A property in downtown Bremerton near the waterfront faces completely different hazards than a home in Port Orchard’s elevated neighborhoods. Downtown properties need robust sewer backup coverage because aging infrastructure makes backup claims more frequent and costly. Elevated properties benefit more from earthquake endorsements than from flood protection. Water intrusion from heavy rainfall and aging gutters affects roughly 10% of homeowners annually, yet many national carriers quote standard policies that exclude sump pump and water backup coverage or charge substantially more for it. Local agents assess your specific block, foundation type, roof age, and proximity to water sources before quoting, then bundle coverage that actually matches your exposure rather than applying a one-size-fits-all approach. An independent agency representing multiple carriers can match your exact risk profile to the insurer offering the best rate and coverage combination for your situation rather than forcing you into a package designed for national averages.
Pacific Northwest Weather Requires Proactive Coverage Decisions
Kitsap’s maritime climate drives specific claim patterns that differ sharply from national trends. Roof damage from wind and hail requires replacement cost value coverage, not actual cash value, because depreciation on roof repairs commonly creates $10,000+ gaps between what you need to spend and what an ACV policy pays. A roof costing $28,000 to replace might pay only $15,000 under depreciated actual cash value. Pipe freezing in winter affects properties with exposed plumbing or inadequate insulation, and repair costs range from $5,000 to $25,000 depending on severity. A local bundled policy should include equipment breakdown coverage for HVAC and plumbing systems, which protects against sudden mechanical failure during temperature swings. Bundling these specialized endorsements with auto coverage through a carrier familiar with regional claim patterns typically costs less than adding them to a standard homeowners policy alone. The single deductible feature available through many bundled policies means if your home and vehicle both suffer damage in a severe windstorm, you pay one deductible instead of two, saving $500–$1,500 per incident.
How Local Agents Match Your Property to the Right Coverage
Independent agents in Kitsap County conduct thorough property assessments before recommending coverage. They examine your roof condition, foundation type, distance from water sources, and neighborhood claim history to identify which endorsements matter most for your specific address. This targeted approach prevents you from overpaying for coverage you don’t need while ensuring you don’t skip protection that addresses your actual exposure. National carriers apply broad underwriting rules that miss local nuances; a local agent catches these gaps and fills them with the right endorsements at the right price. When you work with an agency representing multiple carriers, you receive quotes that reflect your true risk profile rather than generic assumptions about Kitsap properties. The next step involves understanding which additional coverage options fit your bundled package and how to review your protection annually.
Maximizing Your Bundled Insurance Package
Add Endorsements That Address Kitsap’s Specific Threats
Your bundled auto and home policy forms a foundation, but real protection emerges when you add endorsements that address Kitsap’s specific threats. Water backup coverage typically costs between $515 and $773 per year for a standard policy and protects against sewer backups and sump pump failures that affect about 10% of homeowners annually. Without this endorsement, a single backup event costs $10,000–$50,000 in cleanup and restoration. Sewer backup claims hit harder in older Bremerton and Port Orchard neighborhoods where municipal infrastructure sits decades past its design life.
Earthquake coverage runs $200–$400 annually and protects structural damage, personal property, and additional living expenses when the Cascadia Subduction Zone delivers one of its 10–15% probability events in the next 50 years. Flood insurance through the National Flood Insurance Program costs $400–$800 yearly depending on your elevation and foundation type, and it’s mandatory if your lender considers your property at risk. Many Kitsap residents skip these because they think standalone policies cost too much, but bundling reduces the total premium by 10–20% compared to adding them separately.
Equipment breakdown coverage protects your HVAC and plumbing systems against sudden mechanical failure during Kitsap’s temperature swings, typically costing $100–$200 annually when bundled. The single deductible feature available through some bundled policies means if your home and vehicle both suffer damage in the same windstorm or other covered event, you pay one deductible instead of two, saving $500–$1,500 per incident.
Update Your Replacement Cost Limits Annually
Construction costs in Washington rose about 15% from 2020 to 2023, so your dwelling replacement limit may now fall short of what it actually costs to rebuild today. Seattle-area rebuilds run roughly $350–$500 per square foot, meaning a 1,500-square-foot property costs about $525,000–$750,000 to rebuild now. If your policy limit hasn’t increased since 2020, you’re significantly underinsured.
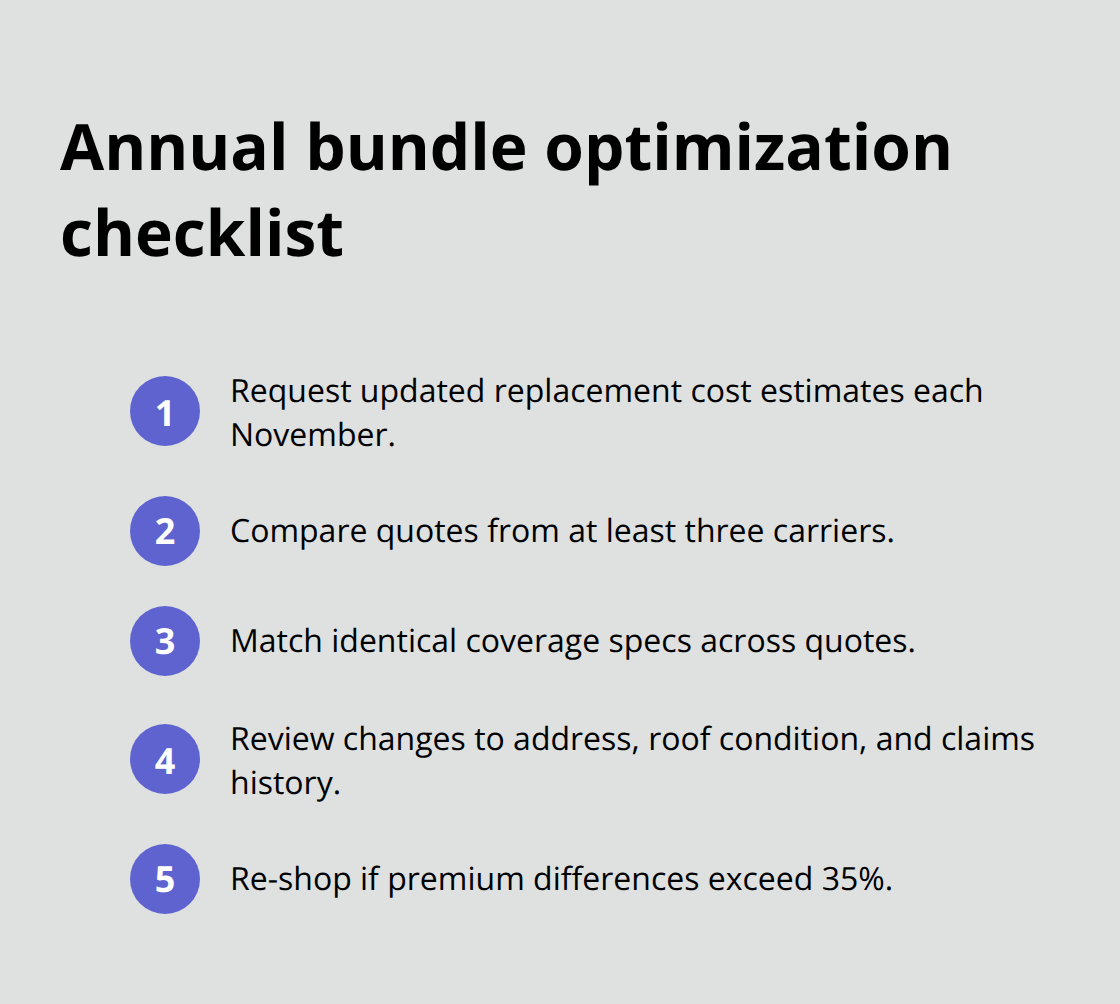
Contact your agent each November to request updated replacement cost estimates and compare quotes from at least three carriers using identical coverage specifications. Premium differences for the same protection regularly exceed 35% between insurers, which means even small changes to your address, roof condition, or claims history can open opportunities to cut costs.
Optimize Your Deductible and Security Discounts
Raising your deductible from $1,000 to $2,500 saves 8–15% on premiums, but only if you maintain liquid cash reserves to cover the higher out-of-pocket expense after a claim. Installing monitored security systems, smoke and carbon monoxide detectors, and smart door locks can yield $150–$300 annual discounts, though you must provide proof the devices function properly.
When you bundle auto and home, verify that any new discounts actually apply to your full bundled premium rather than just one component, since some carriers structure discounts in ways that reduce savings when specialized endorsements are added. This verification step prevents unpleasant surprises when your renewal notice arrives.
Final Thoughts
Bundled auto home insurance in Kitsap County delivers measurable financial results when you shop strategically and work with agents who understand local hazards. The average household saves $1,273 annually through bundling, and competitive shopping across three carriers regularly reveals 35% premium differences for identical protection. These savings compound over years while the convenience of managing one policy instead of two simplifies your life significantly.
What separates successful bundling from missed opportunities is local expertise that addresses Kitsap’s specific threats. The Cascadia Subduction Zone earthquake risk, floodplain exposure affecting 175,000 structures statewide, and Pacific Northwest weather patterns driving 39.4% of claims through wind and hail all require endorsements that national carriers often exclude or price incorrectly. A local agent assesses your exact property location, foundation type, roof condition, and neighborhood claim history to match you with the right coverage at the right price, while raising your deductible from $1,000 to $2,500 cuts premiums by 8–15% and a single deductible feature on some bundled policies saves $500–$1,500 per incident when both your home and vehicle suffer damage simultaneously.
Contact H&K Insurance Agency today to review your current coverage, explore bundling options, and build a policy that protects your Kitsap property against the hazards that actually threaten it. We serve the Puget Sound region with personalized bundled packages that address regional risks without forcing you into generic national templates, and we compare rates across top local and national carriers to deliver both savings and peace of mind.
