Homeowners Insurance Bremerton: Tailored Protection For Your House
Bremerton homeowners face unique weather challenges that put their properties at risk. From heavy rainfall to windstorms, your home needs protection that matches these local threats.
At H&K Insurance Agency, we understand that homeowners insurance in Bremerton isn’t one-size-fits-all. This guide walks you through coverage options, how to pick the right policy, and why having the right protection matters for your peace of mind.
Why Bremerton Homeowners Need Insurance Now
Washington State Weather Creates Real Property Risks
Bremerton’s weather patterns create measurable risks to your property that standard maintenance cannot address. The National Weather Service records that Bremerton receives approximately 56 inches of rainfall annually, nearly double the U.S. average of 38 inches. This excessive moisture leads to rot, mold, and foundation damage that spreads through your home over time. Wind speeds in the Puget Sound region regularly exceed 40 mph during winter storms, causing roof damage and fallen trees that can destroy structures worth hundreds of thousands of dollars.
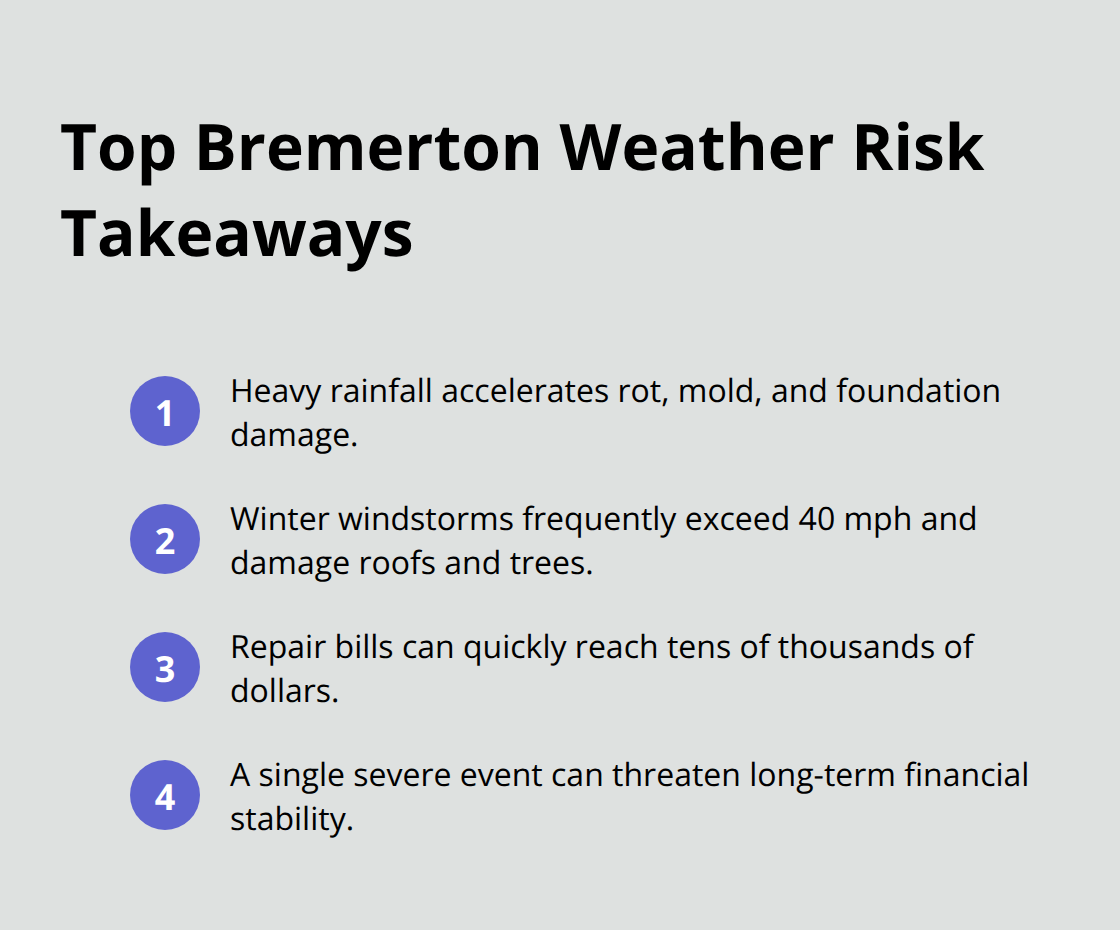
A single windstorm or heavy rain event can force you into personal bankruptcy without homeowners insurance protecting your investment.
The financial impact of weather damage hits hard and fast. Replacing a roof after wind damage costs $8,000 to $15,000 in Washington State, and water damage repairs average $2,500 to $10,000 per incident according to the Insurance Information Institute. These expenses drain savings accounts and force homeowners to take on debt they never anticipated.
Liability Claims Can Devastate Your Finances
Liability exposure affects every homeowner in Bremerton, regardless of how careful you are. If a visitor trips on your property and suffers a serious injury, they can sue you for medical bills, lost wages, and pain and suffering. A jury verdict in a liability case can easily reach $100,000 to $500,000, especially in Washington State where juries tend toward higher awards. Your homeowners insurance covers these liability claims up to your policy limits, protecting your savings and future income from legal judgments.
Lenders Require Insurance Protection
If you have a mortgage, your lender legally requires you to carry homeowners insurance with dwelling coverage equal to at least the loan amount. Bremerton lenders enforce this requirement strictly because they have a financial stake in your property’s protection. Skipping insurance to save money on monthly premiums violates your loan agreement, which gives the lender the right to purchase insurance on your behalf and charge you the full premium plus fees. This forced coverage costs significantly more than policies you select independently.
Understanding these three threats-weather damage, liability exposure, and lender requirements-shows why coverage options matter for your specific situation.
Coverage Options That Fit Your Bremerton Home
Dwelling Coverage: The Foundation of Your Protection
Dwelling coverage forms the foundation of any homeowners policy, and this is where most Bremerton homeowners make their first mistake. You need replacement cost coverage, not actual cash value, because the rebuild cost for a home in Bremerton runs between $150 and $250 per square foot according to recent construction data. A 2,000-square-foot home destroyed by fire or severe weather would cost $300,000 to $500,000 to rebuild, yet many homeowners underinsure by $50,000 to $100,000 to keep premiums low. This gap means you’ll pay out of pocket when disaster strikes.
Calculate your dwelling coverage through a professional home valuation or the rebuild estimator from the National Association of Insurance Commissioners, which accounts for local Bremerton labor and material costs. Your mortgage lender will require dwelling coverage equal to at least your loan balance, but that number often falls short of actual replacement cost, especially if your home has appreciated since purchase.
Personal Property Coverage and High-Value Items
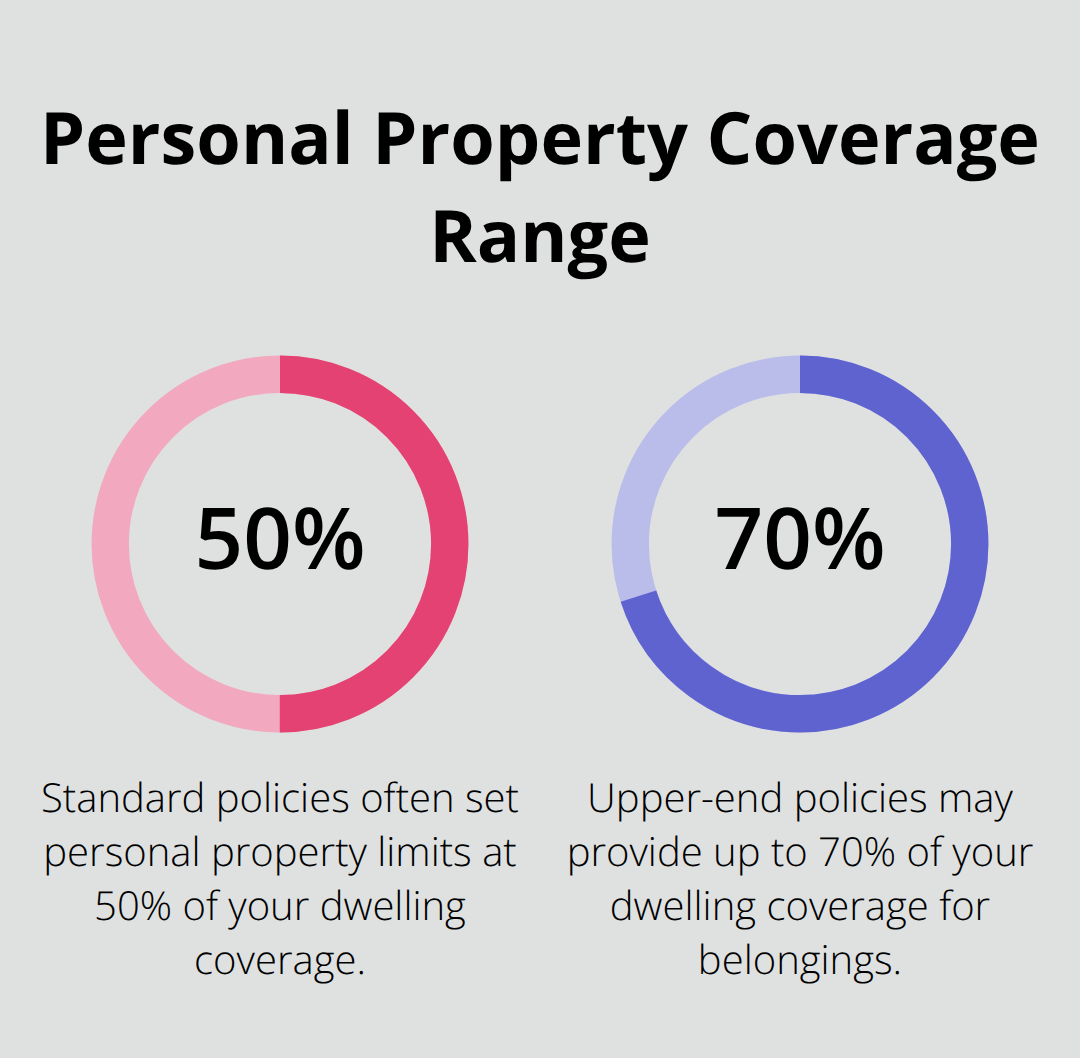
Personal property coverage protects your belongings inside the home, and standard policies cover 50 to 70 percent of your dwelling coverage limit. If your dwelling coverage is $400,000, your personal property coverage maxes out around $200,000 to $280,000, which sounds adequate until you inventory your actual possessions. Electronics, furniture, clothing, and kitchen equipment add up fast, and the Insurance Information Institute reports that average household contents are worth $30,000 to $50,000.
High-value items like jewelry, art, or collectibles need scheduled personal property endorsements because standard policies cap individual items at $1,500 to $2,500. This protection prevents significant losses when valuable possessions suffer damage or theft.
Additional Living Expenses: Staying Afloat During Repairs
Additional living expenses coverage becomes critical when your home becomes uninhabitable after weather damage or fire. Bremerton’s rental market averages $1,500 to $2,000 monthly for comparable housing, and this coverage pays hotel stays, meals, and temporary housing for months while repairs happen. Without this protection, you absorb these costs from your own savings while contractors rebuild your property.
Liability Protection: Shielding Your Assets
Liability protection shields you when someone gets injured on your property or you accidentally damage someone else’s property. Washington State liability awards frequently exceed $100,000, so try minimum coverage of $300,000 to $500,000, especially if you have significant assets or a swimming pool. This protection prevents a single accident from wiping out your financial security.
Medical payments coverage handles smaller injuries without involving liability claims, covering up to $5,000 in medical expenses for guests injured on your property. This coverage prevents lawsuits over minor incidents and demonstrates responsibility to visitors on your property.
Now that you understand what coverage options exist, the next step involves comparing policies from multiple carriers to find the right combination for your situation and budget.
How to Choose the Right Homeowners Policy for Bremerton
Calculate Your Home’s True Replacement Value
Start with your home’s replacement value, because this number drives every coverage decision you make. The rebuild cost in Bremerton ranges from $150 to $250 per square foot depending on construction quality and current material prices, so a 2,000-square-foot home could cost anywhere from $300,000 to $500,000 to rebuild from the ground up. Contact a local contractor or use the National Association of Insurance Commissioners rebuild estimator to get a realistic figure based on your specific home. This number should become your dwelling coverage limit, not the amount your mortgage lender requires. Many Bremerton homeowners find their lender’s requirement falls $50,000 to $100,000 short of actual replacement cost, leaving them underinsured when disaster strikes. Once you know your replacement value, you can compare what different carriers actually offer for that coverage level.
Compare Quotes Across Multiple Carriers
Comparing quotes from multiple carriers reveals dramatic price differences for identical coverage in Bremerton. One homeowner might pay $1,200 annually for $400,000 in dwelling coverage while another pays $1,800 for the same protection, depending on which carrier underwrites the risk. Get quotes from at least three carriers, and make sure each quote includes the same dwelling coverage amount, liability limits, and deductible so you’re comparing apples to apples. This approach takes time but saves thousands over your policy’s lifetime.
Leverage Bundling Discounts for Maximum Savings
Many Bremerton homeowners overlook bundling options that can reduce your total insurance costs significantly. Bundling typically saves 10 to 25 percent on your homeowners premium, so a policy that costs $1,500 standalone might drop to $1,125 when combined with your auto coverage.
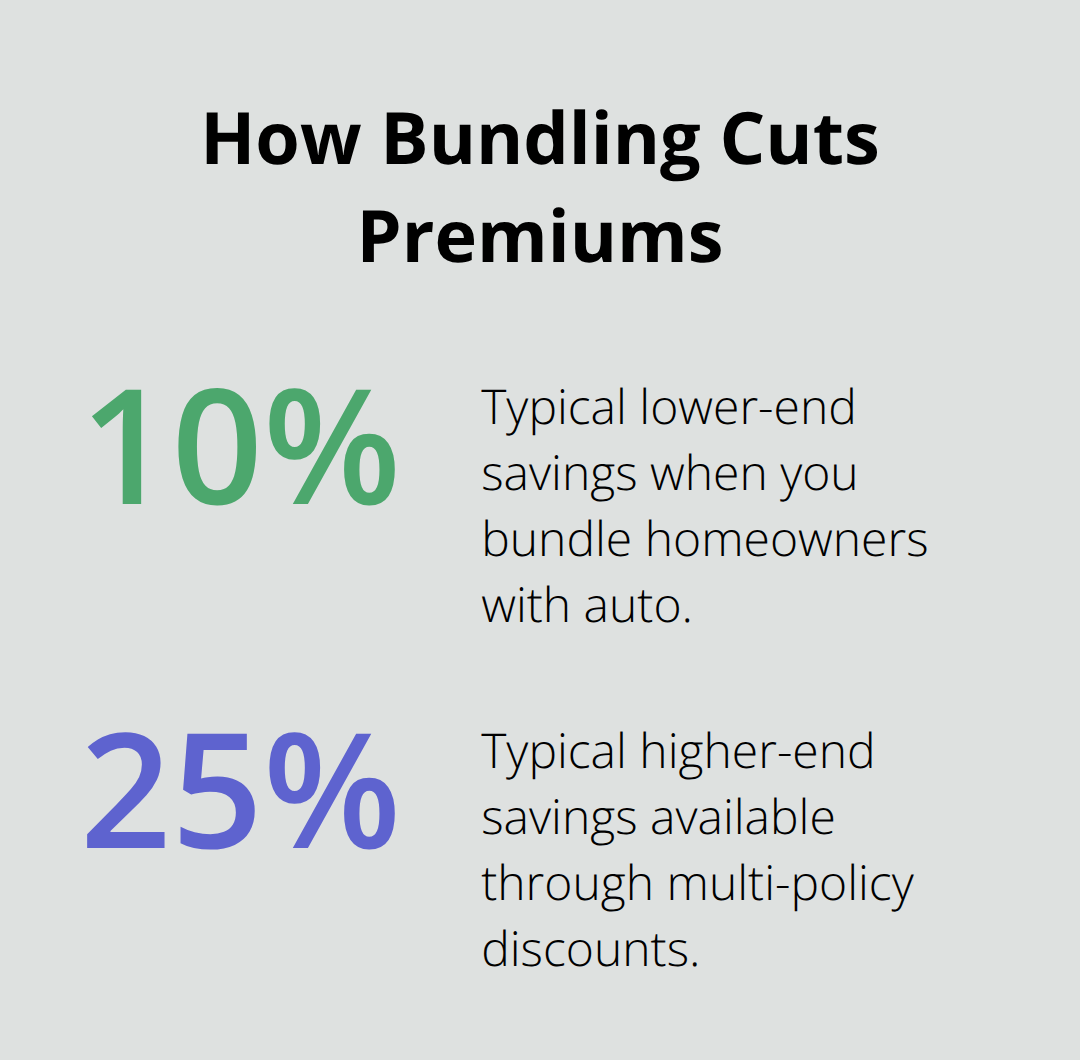
Ask about multi-policy discounts before finalizing any quote, because this single factor often matters more than shopping around for marginal rate differences. We at H&K Insurance Agency represent multiple top local and national carriers, which means we can compare rates across different companies and show you exact bundling savings when you combine homeowners coverage with auto insurance or other policies. This comparison process helps you find the right protection at competitive prices without spending hours contacting individual insurers.
Final Thoughts
Bremerton homeowners face real weather threats, liability exposure, and lender requirements that demand serious insurance protection. The rainfall, windstorms, and liability risks we covered throughout this guide aren’t theoretical concerns-they’re measurable dangers that affect your property value and financial security every single year. Your dwelling coverage needs to match your home’s actual replacement cost, not just your mortgage balance, and personal property protection plus liability limits should reflect your specific situation and assets.
Comparing quotes across multiple carriers and exploring bundling options can save you thousands without sacrificing the protection your home deserves. Calculate your home’s true replacement value using local construction costs, gather quotes from at least three carriers with identical coverage levels, and ask about bundling discounts before making your final decision. Don’t let premium savings tempt you into underinsuring your dwelling or liability protection, because a single weather event or liability claim can cost far more than the premiums you’d save by cutting corners.
Contact H&K Insurance Agency to get personalized quotes for homeowners insurance in Bremerton and discover how much you could save while protecting your home with the right coverage. Our team understands the specific risks that Bremerton properties face and can customize your coverage for flood, earthquake, and other regional threats. We represent multiple top carriers, which means we compare rates across different companies and show you exact savings when you bundle homeowners insurance with auto coverage or other policies.
