Puget Sound Homeowners Policy Demystified: Affordable Protection For Your Home
Your Puget Sound homeowners policy is one of the most important financial decisions you’ll make as a homeowner. Yet most people don’t understand what their coverage actually includes or whether it’s enough for our region’s unique risks.
At H&K Insurance Agency, we’ve helped hundreds of local homeowners navigate these decisions and find protection that fits their budget. This guide walks you through what you need to know.
What Washington State Actually Requires for Homeowners Insurance
Your Lender’s Minimum vs. Your Real Protection
Washington State law doesn’t mandate that you carry homeowners insurance, but your mortgage lender will. If you have a loan on your home, your lender requires coverage that protects their financial interest in the property. This is standard across all major lenders. The minimum coverage your lender demands typically includes dwelling protection, which covers the structure itself.
What your lender requires and what actually protects you are two different things. Most lenders care about one thing: if your house burns down, they get paid. They don’t care whether you can replace your personal belongings or rebuild your life after a disaster. This gap between lender requirements and real protection is where most Puget Sound homeowners get into trouble.
What Standard Policies Actually Cover
A standard policy usually covers dwelling, personal property, liability, and additional living expenses, but the coverage limits and exclusions vary dramatically between policies. Your dwelling coverage pays to rebuild your home’s structure. Personal property coverage replaces your belongings. Liability coverage protects you if someone gets injured on your property.
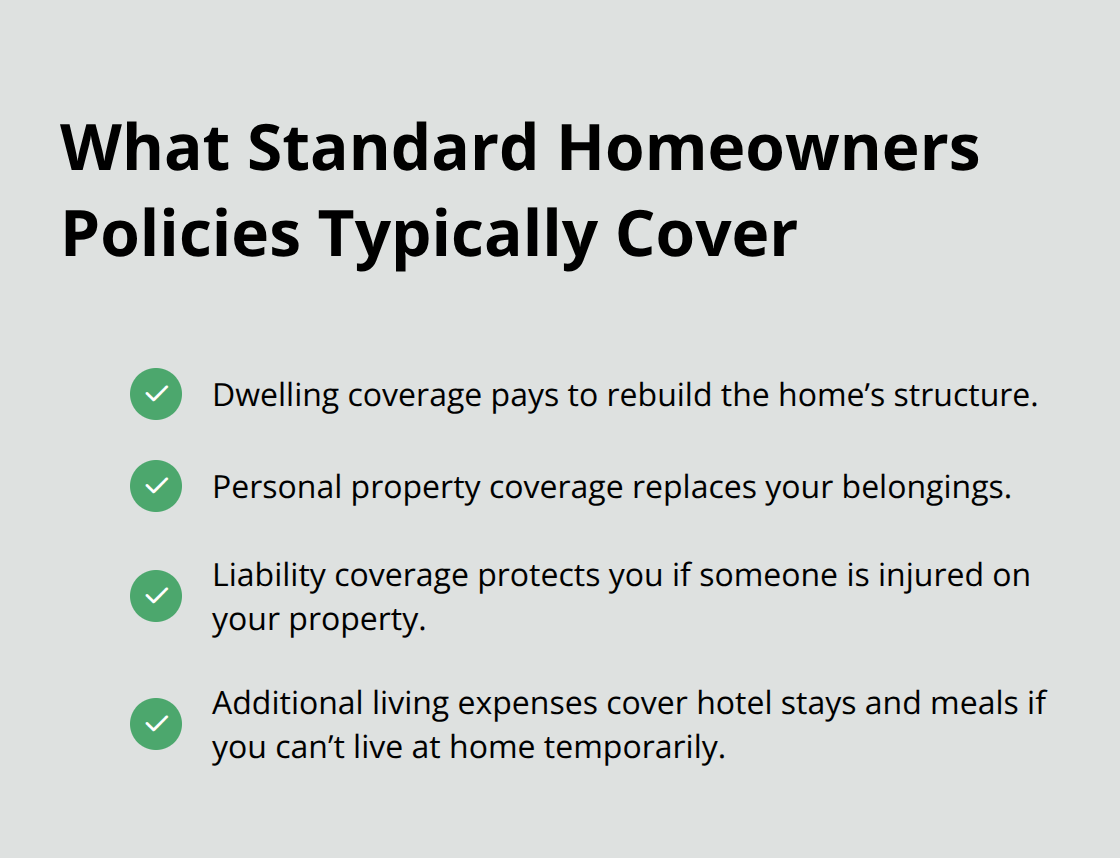
Additional living expenses cover hotel stays and meals if you can’t live in your home temporarily.
The problem is that these coverages come with limits and exclusions that don’t match Puget Sound’s specific risks. You need to understand what gaps exist in your current protection before disaster strikes.
Why Puget Sound Weather Creates Coverage Gaps
Washington’s weather and geography create specific risks that standard policies often handle poorly. The Pacific Northwest experiences significant wind events during winter storms in the Puget Sound region according to the National Weather Service. Water damage from heavy rain, flooding, and roof leaks ranks as one of the most common insurance claims in our area.
Earthquakes pose another serious threat since we sit near the Cascade Subduction Zone, yet most standard homeowners policies exclude earthquake damage entirely. You need to add earthquake coverage as a separate endorsement. Flood damage is similarly excluded from standard policies, which shocks many homeowners who discover this gap only after water enters their basements during heavy rainfall or when nearby waterways overflow.
Location and Home Age Matter More Than You Think
The difference between what your policy covers and what you actually need often comes down to where you live and your home’s specific characteristics. A home near Puget Sound faces different risks than one on a hillside in Tacoma. Older homes with aging roofs and plumbing systems need different protection levels than newer construction. Your home’s proximity to water, elevation, and structural condition all influence which coverage types you actually need.
This is why customizing your policy matters far more than simply accepting whatever quote arrives in your mail or email. The next section walks you through how to add the specific protections that Puget Sound homeowners actually need.
Customizing Your Policy for Puget Sound’s Real Threats
Earthquake and Flood Coverage You Actually Need
Standard homeowners policies in Washington leave you exposed to the exact disasters most likely to hit our region. Earthquake and flood coverage don’t come automatically, and your dwelling limit might fall thousands of dollars short of what rebuilding actually costs in today’s Puget Sound market. The Federal Emergency Management Agency reports that the average flood claim exceeds $30,000, yet most homeowners assume their standard policy covers water damage. It doesn’t. Similarly, the U.S. Geological Survey identifies the Cascadia Subduction Zone as capable of producing magnitude 9.0 earthquakes, and when one occurs, standard policies won’t pay a dime toward repairs.
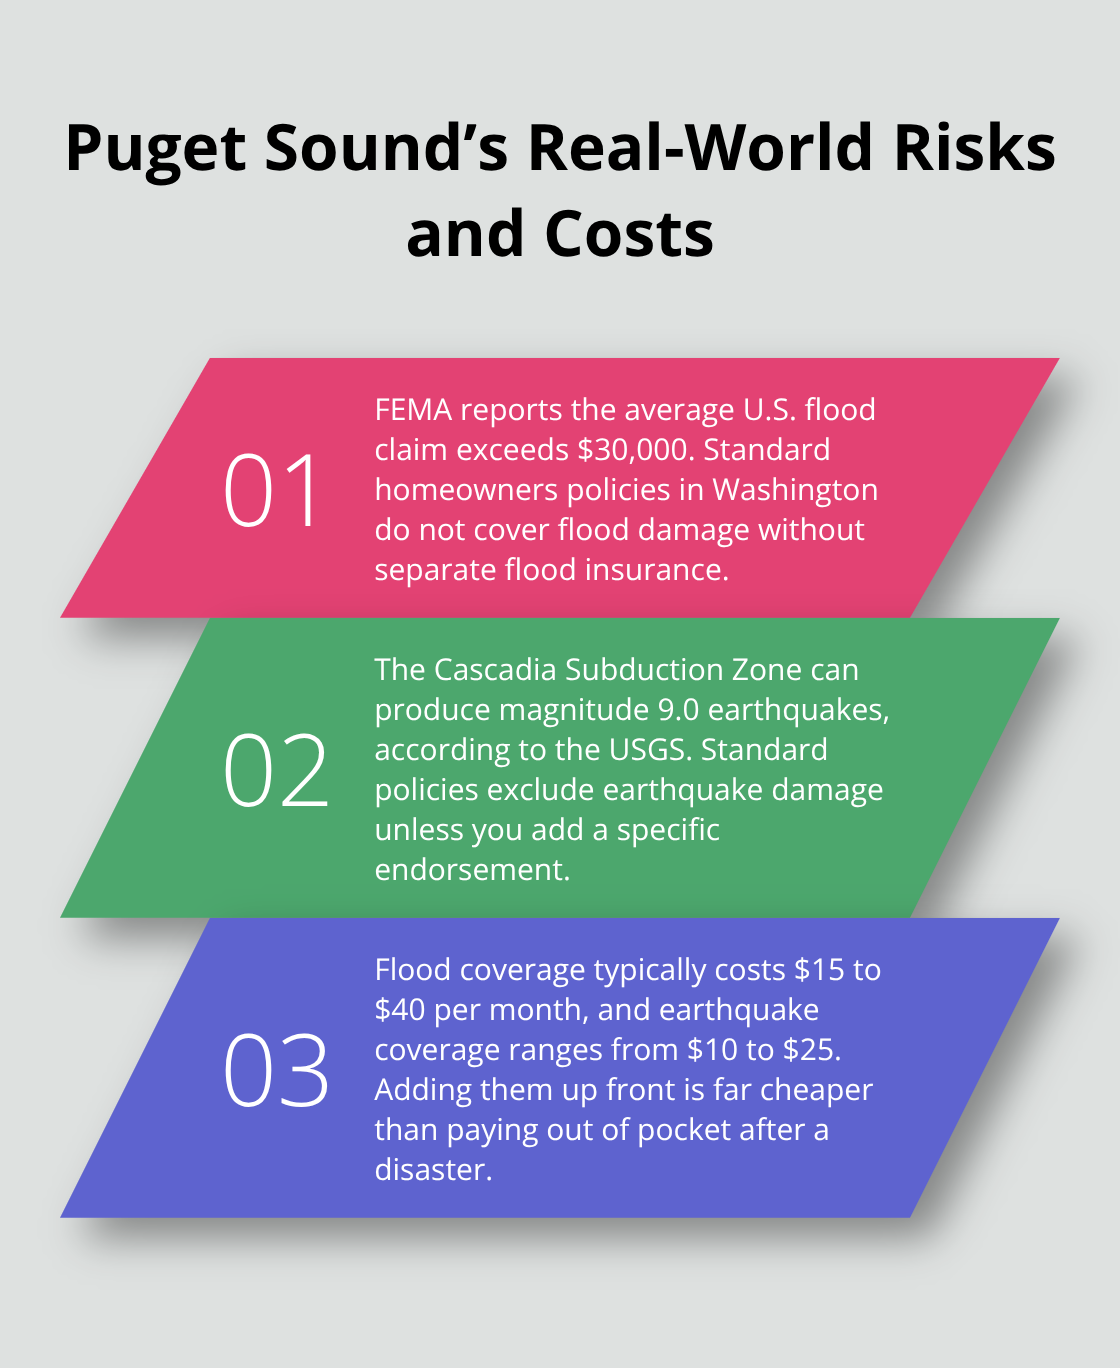
Adding these coverages costs far less than most homeowners expect. Flood protection typically runs $15 to $40 monthly, while earthquake coverage ranges from $10 to $25 depending on your home’s age and location. The real mistake isn’t adding these endorsements-it’s waiting until after a disaster to realize you needed them.
Adjusting Dwelling Limits to Match Current Home Values
Your coverage limits and deductibles directly determine whether you can actually rebuild after a loss. Puget Sound home values have climbed significantly over the past five years, yet many homeowners never adjusted their dwelling limits to match. If your home is insured for $400,000 but rebuilding costs $550,000, you absorb that $150,000 gap yourself.
Work with an agent to get an accurate replacement cost estimate specific to your neighborhood and home’s construction type. This step prevents the painful discovery that your coverage falls short when you need it most.
Bundling and Strategic Deductible Choices
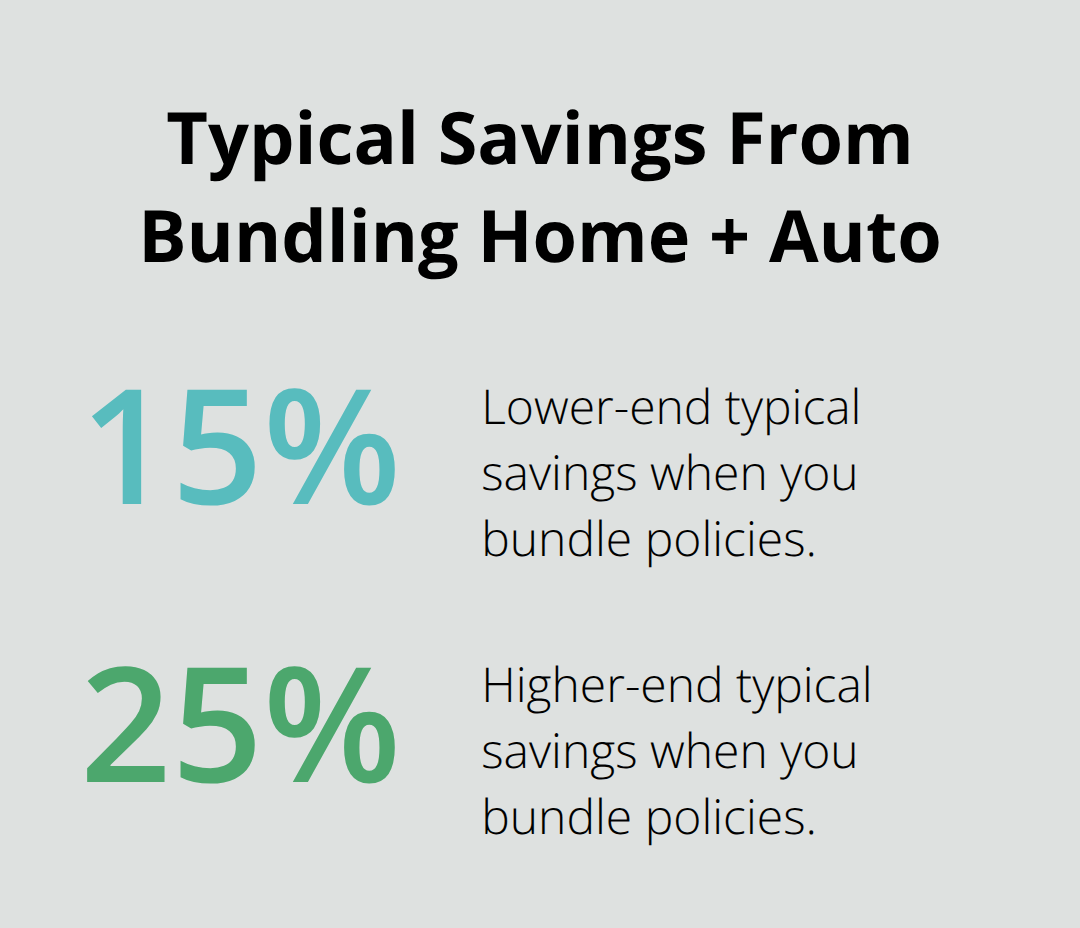
Bundling your homeowners policy with auto insurance typically saves 15 to 25 percent on your total premium, which frees up money for those additional coverages you actually need. As a locally owned, independent agency serving the Puget Sound region, H&K Insurance Agency represents multiple top carriers to find combinations that maximize your savings while closing coverage gaps.
Your location within the Puget Sound area also matters enormously. Homes near water or in areas prone to wind damage need different protection strategies than homes on elevated terrain. Older homes with original plumbing and roofs face higher water damage risk and may benefit from lower deductibles on water-related claims.
Getting Quotes That Reflect Your Specific Situation
Request quotes that reflect your specific address, home age, and construction details rather than generic estimates based on zip code alone. An agent who understands Puget Sound’s regional hazards will identify which coverage gaps pose the greatest risk to your particular property. Once you understand what protection you need, the next step involves recognizing the common mistakes that leave homeowners underinsured when claims actually happen.
Three Mistakes That Leave Puget Sound Homeowners Dangerously Underprotected
Accepting Outdated Dwelling Limits Without Verification
Most Puget Sound homeowners accept whatever dwelling limit the insurance company suggests without verifying it matches actual rebuilding costs in their neighborhood. If your home is insured for $450,000 but a total loss actually costs $600,000 to rebuild in your zip code, you absorb that $150,000 shortfall yourself. This mistake becomes catastrophic after a major fire or earthquake.
Your coverage limits and deductibles directly determine whether you can actually rebuild after a loss. Work with an agent to obtain an accurate replacement cost estimate specific to your neighborhood and home’s construction type. This step prevents the painful discovery that your policy won’t cover your actual loss when disaster strikes.
Overlooking Regional Hazards and Hidden Deductibles
The second costly error involves ignoring regional hazards that fall outside standard policy language. Windstorms cause significant damage across the Puget Sound region during winter months, but many homeowners don’t realize their basic policy includes a windstorm deductible of 5 to 10 percent of dwelling coverage instead of the standard $500 or $1,000 deductible. This means a windstorm claim on a $500,000 home could require you to pay $25,000 out of pocket before coverage kicks in.
Water damage from heavy rainfall, roof leaks, and saturated soil presents an even bigger problem because standard policies exclude water intrusion entirely unless you add specific endorsements. Homeowners living within five miles of Puget Sound or in areas with poor drainage face exposure to their most likely loss scenario without proper protection. Flood protection typically costs $15 to $40 monthly, while earthquake coverage ranges from $10 to $25 depending on your home’s age and location. The real mistake isn’t adding these endorsements-it’s waiting until after a disaster to realize you needed them.
Failing to Update Coverage After Major Life Changes
The third mistake involves treating insurance as a set-it-and-forget-it purchase rather than a policy that needs adjustment after major life changes. When you complete a home renovation, add a deck, finish a basement, or install new appliances and furniture, your personal property and dwelling coverage limits become outdated immediately. Similarly, if you’ve paid down your mortgage significantly or added substantial equity, your liability limits may fall short of your actual net worth exposure.
Major life events like retirement, inheriting valuable items, or converting part of your home to a rental property all demand immediate coverage adjustments. An updated home replacement cost estimate from a qualified agent every two to three years costs nothing but prevents the devastating realization that your policy won’t cover your actual loss when disaster strikes.
Final Thoughts
The gap between what you pay for a Puget Sound homeowners policy and what you actually receive often comes down to one decision: working with someone who understands your region’s specific risks. Generic online quotes treat all Puget Sound homes the same, which means they miss the protection gaps that matter most to you. At H&K Insurance Agency, we represent multiple top carriers, which gives us the ability to compare rates across different companies and find combinations that work for your budget.
Local independent agents know which carriers offer the best rates for homes near water, which companies provide competitive pricing for older structures, and which insurers actually pay claims without fighting you on coverage details. We also identify discounts you won’t find on comparison websites-home safety features like updated electrical systems, reinforced roofing, or installed fire suppression systems lower your premiums, while a clean claims history qualifies you for loyalty discounts. Spending an extra $30 monthly on earthquake and flood endorsements costs $360 annually but protects you from a $150,000 gap in coverage after a disaster.
Contact H&K Insurance Agency to compare rates and find protection that actually fits your needs. We serve the Puget Sound region as a locally owned independent agency and customize packages that close your coverage gaps while maximizing your savings through bundling and discounts.
