Bremerton Rental Property Policy: A Local Landlord’s Guide To Coverage
Owning rental property in Bremerton comes with unique insurance challenges that standard homeowners policies simply won’t address. A Bremerton rental property policy protects your investment from tenant-related liability, loss of income, and property damage in ways a regular policy can’t.
We at H&K Insurance Agency help landlords navigate these coverage gaps and find policies that match their specific needs. This guide walks you through the essential coverage types, how to compare quotes, and why local expertise matters for your rental business.
Why Rental Properties Need Different Insurance Than Your Primary Home
Standard Homeowners Policies Won’t Cover Rental Income
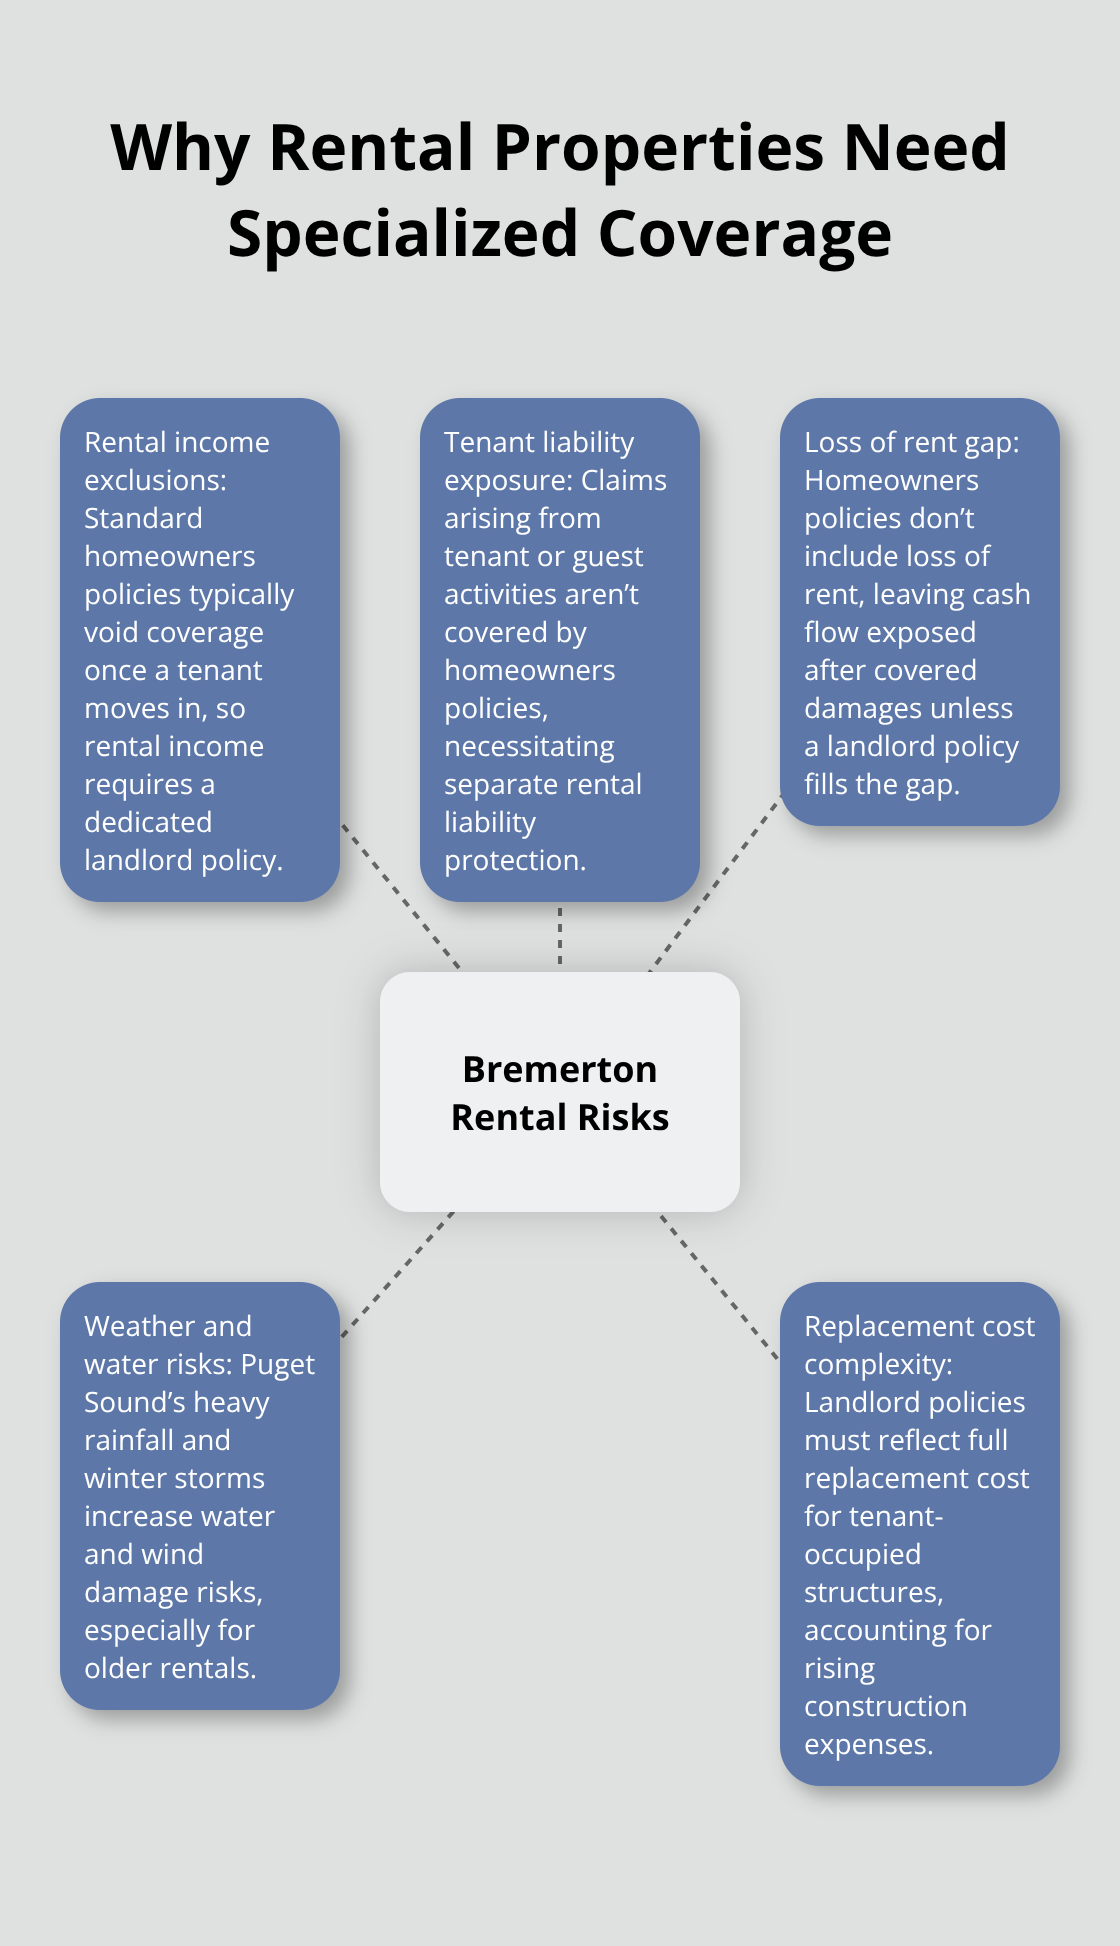
Standard homeowners policies flatly reject rental properties. Insurers will not discuss coverage once they learn the property generates income. The moment a tenant moves in, your homeowners policy becomes void for that dwelling. Most carriers include explicit exclusions stating they will not cover owner-occupied homes used as rentals, investment properties, or any structure where someone other than the owner lives. This isn’t arbitrary-it reflects the fact that tenant-occupied properties carry fundamentally different risk profiles.
Insurers view rental units as higher-risk due to increased foot traffic, less owner oversight, and tenant-caused damage that homeowners insurance simply will not touch.
How Liability Coverage Differs for Rental Properties
The coverage gaps between owner-occupied and rental properties are substantial and directly impact your financial exposure. Standard homeowners policies provide personal liability protection if someone is injured on your property, but rental liability works differently because tenants and their guests create separate liability exposure. Your homeowners policy won’t protect you against claims arising from tenant activities or guest injuries on rental premises. Rental liability policies address this gap by covering bodily injury and property damage claims that tenants or their visitors initiate. This distinction matters because tenant-related incidents occur far more frequently than owner-occupied property claims.
Loss of Rent and Building Coverage Gaps
Loss of rent coverage does not exist in homeowners policies at all, yet this protection is essential for landlords. If a fire or major damage forces tenants out, you still have a mortgage and property taxes due. Building coverage limits also differ significantly between policy types. A homeowners policy covers the structure and permanent fixtures, but rental policies must account for the full replacement cost of a building occupied by tenants who have no financial stake in its upkeep.
Regional Weather and Water Damage Risks
Water damage and weather events require expanded protection in Bremerton specifically. The Puget Sound region receives around 55 inches of annual rainfall, concentrated heavily between October and March, and wind damage from winter storms affects older rental properties disproportionately. A rental policy accounts for these regional weather patterns and tenant-related water damage scenarios that homeowners coverage ignores entirely. Tenants often cause water damage through negligence-leaving windows open during storms, failing to report leaks, or misusing plumbing fixtures-and standard policies exclude these tenant-caused losses. Underinsured landlords in Bremerton regularly face five-figure out-of-pocket costs when tenant damage or weather events occur, costs that proper rental coverage would have prevented.
Finding the Right Coverage for Your Bremerton Investment
The financial stakes of inadequate coverage make selecting the right rental policy a priority. Multiple carriers operate in the Bremerton market, each offering different coverage limits, deductibles, and pricing structures for landlord policies. Comparing quotes from several insurers reveals significant variations in cost and protection levels for the same property type.
What Coverage Every Bremerton Landlord Must Carry
Building Coverage Protects Your Structure’s Full Replacement Cost
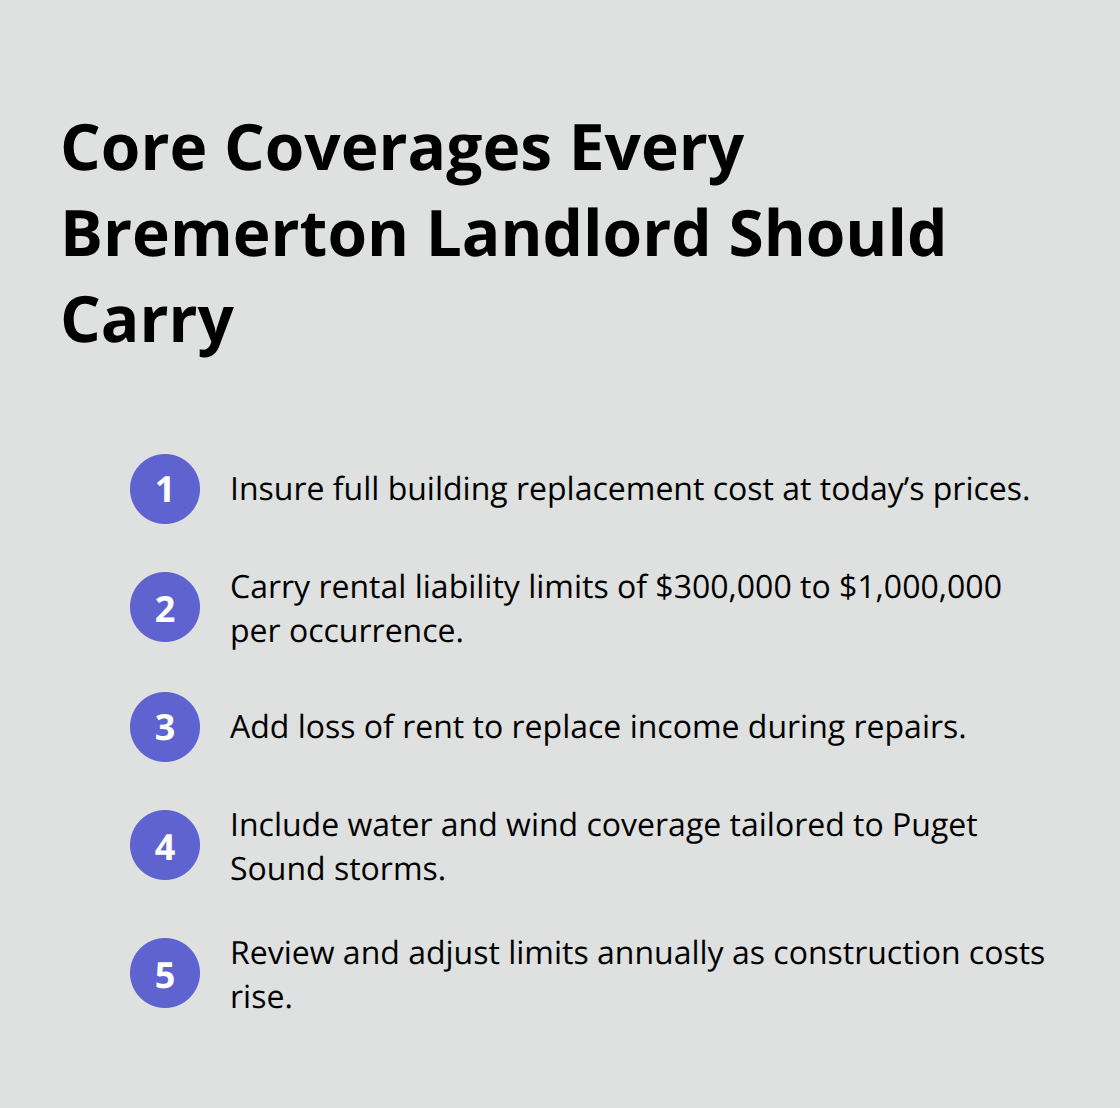
Building coverage forms the financial foundation of any rental property policy in Bremerton, and it must reflect the full replacement cost of your structure, not just its current market value. If your building costs $400,000 to replace today, your coverage limit should be $400,000 or higher, because construction costs in Washington State have increased significantly in recent years. Underestimating replacement cost leaves you exposed to catastrophic out-of-pocket expenses after fire, storm damage, or other total loss events.
The coverage includes the building’s frame, roof, walls, flooring, and permanent fixtures like built-in appliances and bathroom fixtures, but excludes tenant belongings and temporary items. Many landlords mistakenly assume their property value equals replacement cost, then face massive gaps when damage occurs and construction quotes arrive 30-40% higher than expected.
Liability Protection Shields You From Injury Claims
Liability protection separates landlords who stay solvent from those who face financial ruin after tenant or guest injuries. A single slip-and-fall claim can easily exceed $100,000 in medical costs, lost wages, and pain-and-suffering awards, especially if a guest suffers permanent injury on your property. Standard rental liability policies typically offer $300,000 to $1 million in coverage per occurrence, with most Bremerton landlords carrying $500,000 minimums.
This coverage pays legal defense costs and settlements when someone is injured due to property conditions you’re responsible for maintaining, such as broken stairs, poor lighting, or inadequate handrails. The protection applies to tenant injuries and guest injuries alike, covering scenarios that standard homeowners policies explicitly exclude.
Loss of Rent Coverage Maintains Your Income Stream
Loss of rent coverage protects your income stream when fires, storms, or other insured events make the property unlivable and tenants must vacate temporarily. If your property generates $2,400 monthly rent and a kitchen fire forces tenants out for three months, loss of rent coverage reimburses that $7,200 gap while repairs proceed and you still owe your mortgage and property taxes. This coverage prevents you from absorbing both lost income and ongoing property expenses simultaneously.
Water Damage and Weather Events Require Regional Protection
Water damage and weather events require expanded protection in the Puget Sound region specifically, since Bremerton averages 55 inches of annual rainfall concentrated between October and March, and winter storms regularly produce wind damage exceeding 50 mph. Tenant-caused water damage through negligence (like leaving windows open during storms or failing to report leaks) represents the single largest claim category for rental properties in Washington State.
A standard rental policy covers these scenarios, but only if you select appropriate water damage and weather event limits rather than relying on basic coverage that excludes tenant negligence. Tenants often cause water damage through actions that homeowners policies would never cover, making this protection essential for Bremerton properties.
Adjusting Coverage as Property Values Rise
Construction costs and property values shift annually, which means your coverage limits can fall behind without regular review. When property values or construction costs increase, your coverage limits must increase proportionally to maintain adequate protection. Waiting until after damage occurs guarantees you’ll be underinsured, leaving you to cover the difference from your own pocket. The next section walks you through comparing quotes from multiple carriers to find the right policy at the right price for your specific property.
How to Choose the Right Coverage Limits and Deductibles
Calculate Your True Replacement Cost
Replacement cost is where most Bremerton landlords make their first critical mistake. You cannot eyeball this number or rely on what you paid for the property five years ago. The national average increase in construction costs is approximately 5.41% year-over-year, meaning property rebuilding costs continue to rise significantly. You need a professional replacement cost assessment before comparing quotes, not after. This assessment accounts for square footage, construction type, local labor rates, and material costs specific to Bremerton. Many insurance carriers offer free replacement cost analyses to help you establish accurate coverage limits from the start. Without this baseline, you are essentially guessing at your protection level.
Select Deductibles Based on Your Financial Position
Deductibles directly control what you pay out of pocket when claims happen, and this choice separates smart landlords from those who pay too much in premiums. A $500 deductible costs roughly 15-20% more annually than a $1,000 deductible on comparable Bremerton rental policies, but that $500 annual savings disappears the moment damage occurs and you owe $1,000 instead of $500. Most Bremerton landlords with multiple properties or strong cash reserves should select $1,000-$2,500 deductibles to reduce premium costs significantly. If you own a single property with limited reserves, a $500-$750 deductible makes sense despite higher premiums.
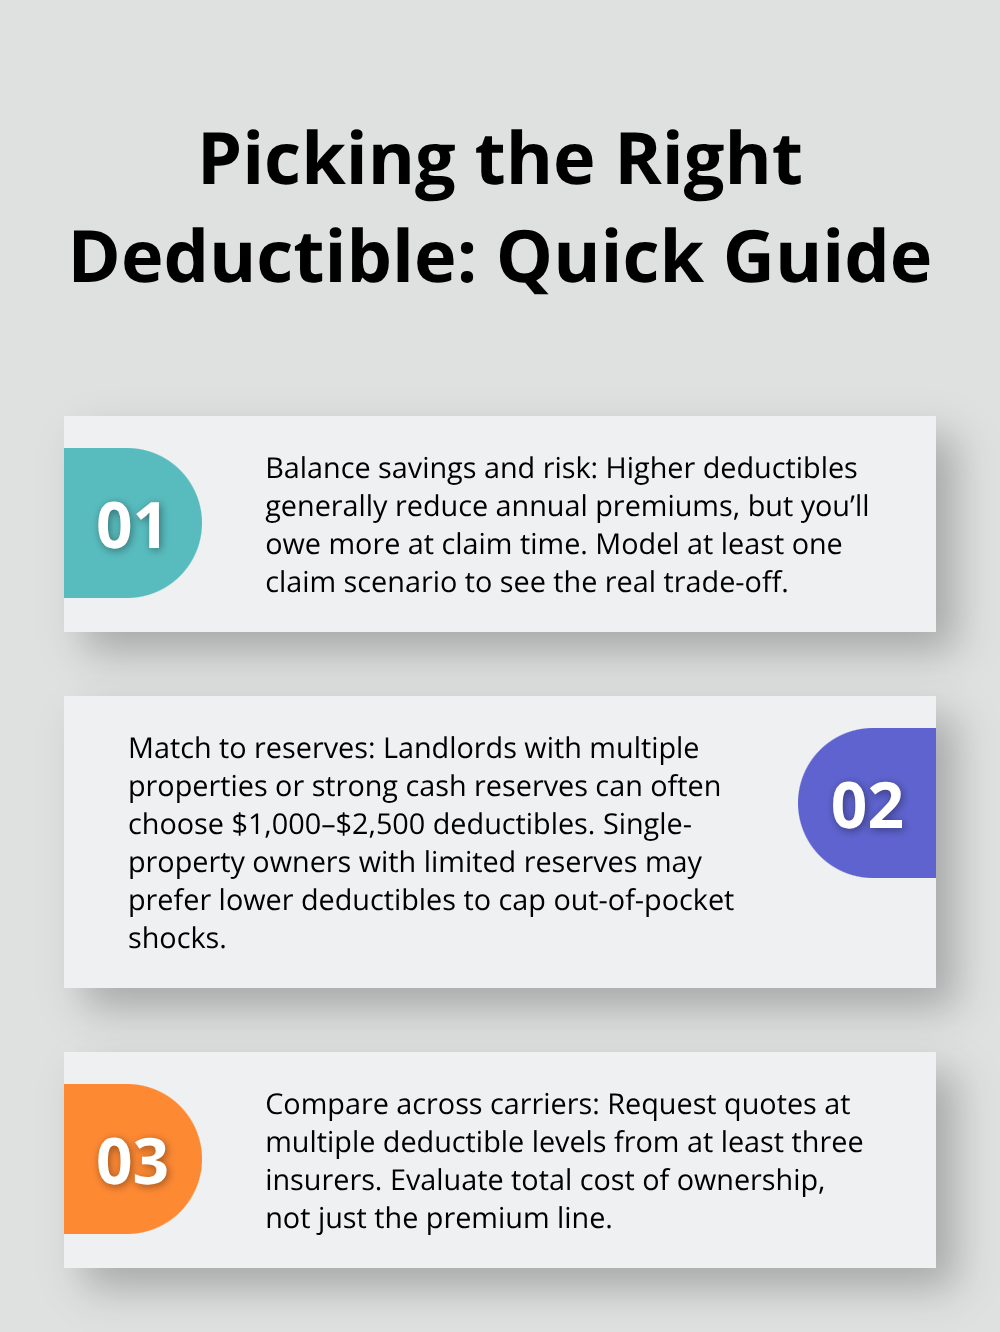
You must compare total cost of ownership, not just annual premium. Request quotes at multiple deductible levels from at least three carriers to see how this choice affects your bottom line.
Bundle Policies to Lower Your Total Costs
Bundling rental coverage with auto, boat, or personal umbrella policies typically reduces your total insurance costs by 10-25% across all policies combined. As an independent agency representing multiple top local and national carriers, H&K Insurance Agency can show you exactly how bundling affects your specific situation rather than forcing you into one carrier’s package. You should get quotes from independent agents who represent multiple insurers, not captive agents tied to a single company. The difference in pricing and available coverage options between carriers is substantial enough to justify spending 30 minutes comparing three to five quotes before deciding.
Final Thoughts
Protecting your Bremerton rental property requires building coverage that reflects your full replacement cost, liability protection against tenant and guest injury claims, and loss of rent coverage that maintains your income stream when properties become uninhabitable. Water damage and weather event protection matters specifically in the Puget Sound region, where annual rainfall and winter storms create tenant-caused damage scenarios that standard homeowners policies exclude entirely. A single fire, storm, or injury claim can wipe out years of rental income and leave you facing five-figure out-of-pocket expenses without these coverages working together.
Selecting the right Bremerton rental property policy demands more than shopping for the lowest premium-you need an agency that represents multiple carriers, understands local market conditions, and shows you exactly how deductible choices and bundling options affect your total cost of ownership. Independent agencies outperform captive agents because they compare rates across multiple insurers rather than forcing you into one company’s limited options. A local agency also knows which carriers offer the best terms for Bremerton properties specifically, accounting for regional weather patterns and tenant-related risks that national call centers miss entirely.
We at H&K Insurance Agency serve landlords throughout the Puget Sound region by representing multiple top local and national carriers, which means we compare rates and customize packages so you get the right protection at competitive prices. Our team handles bundling, specialty coverages, and the detailed replacement cost assessments that prevent underinsurance. Start by requesting a free replacement cost analysis and quotes at multiple deductible levels-this 30-minute conversation reveals exactly what your rental property protection costs and prevents the costly mistakes that leave landlords exposed.
