Bremerton Rental Property Coverage: Guard Your Investment
Owning rental property in Bremerton comes with real financial exposure. Standard homeowners insurance won’t protect you from the specific risks that come with tenants and rental operations.
We at H&K Insurance Agency see landlords lose thousands every year because they’re underinsured. The right Bremerton rental property coverage makes the difference between a manageable loss and a financial disaster.
Why Landlord Insurance Differs From Home Coverage
Standard homeowners insurance explicitly excludes rental properties. Most insurers won’t cover a home you rent to tenants, and those who do charge significantly more without the specialized protections landlords actually need. The difference matters enormously when a tenant’s guest gets injured on your property or a fire forces you to evict tenants mid-lease.
How Homeowners and Landlord Policies Protect Different Risks
A homeowners policy protects your primary residence and personal liability from accidents that occur there. Landlord insurance protects your investment property from tenant-related risks, loss of rental income, and liability claims specific to rental operations. The difference matters enormously when a tenant’s guest gets injured on your property or a fire forces you to evict tenants mid-lease.
The Financial Gaps Standard Policies Leave Open
A standard homeowners policy won’t cover loss of rent if your property becomes uninhabitable. If a fire damages your Bremerton rental, your homeowners policy pays to rebuild the structure, but you lose the monthly rent from your tenant while repairs happen. That’s a direct financial hit homeowners policies ignore completely.
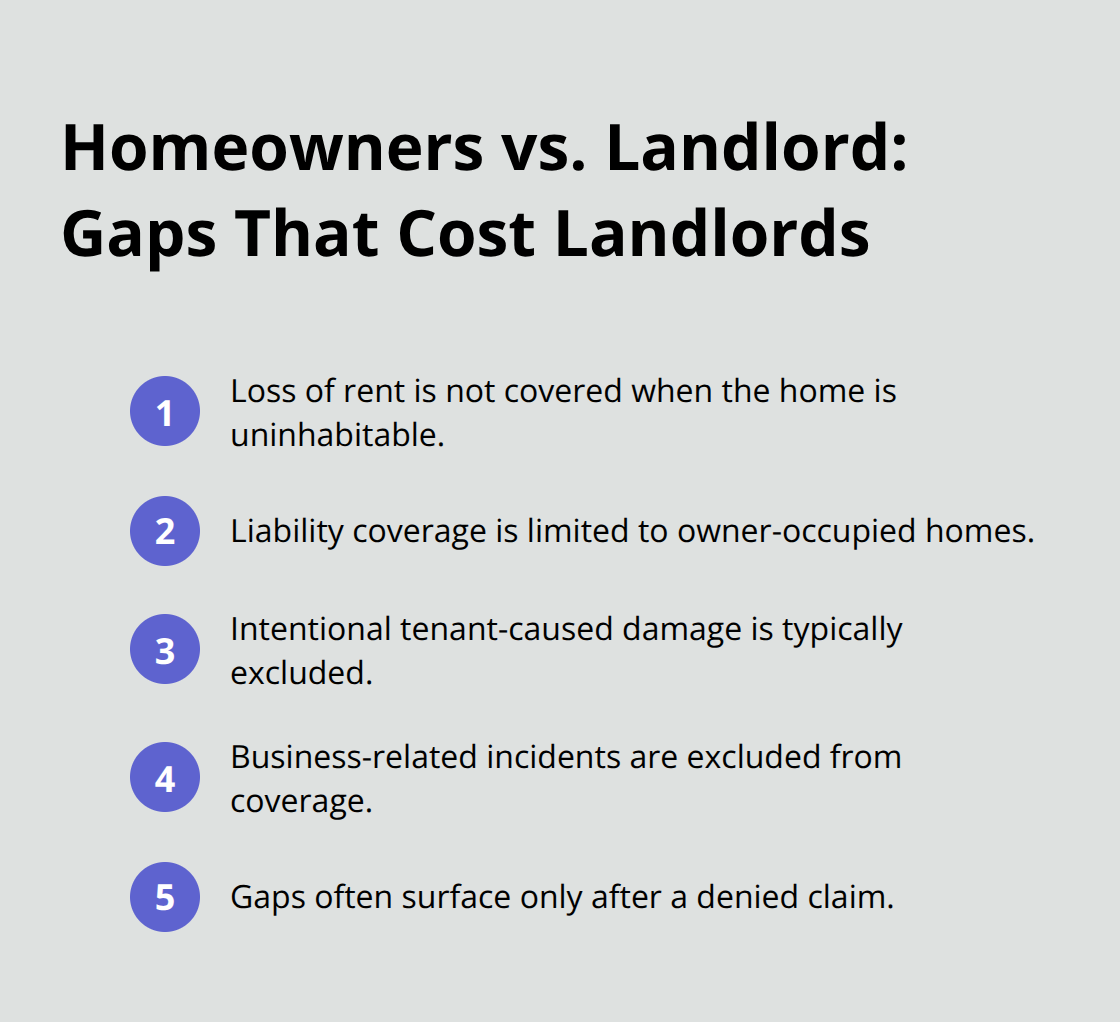
Most homeowners policies also limit liability coverage to owner-occupied homes, meaning if someone gets hurt on your rental property, you may face claims without adequate protection. Additionally, standard policies exclude damage from tenant actions like intentional destruction or business-related incidents. Landlords often learn these gaps exist only after filing a claim and discovering their coverage doesn’t apply.
What Landlord Insurance Actually Covers
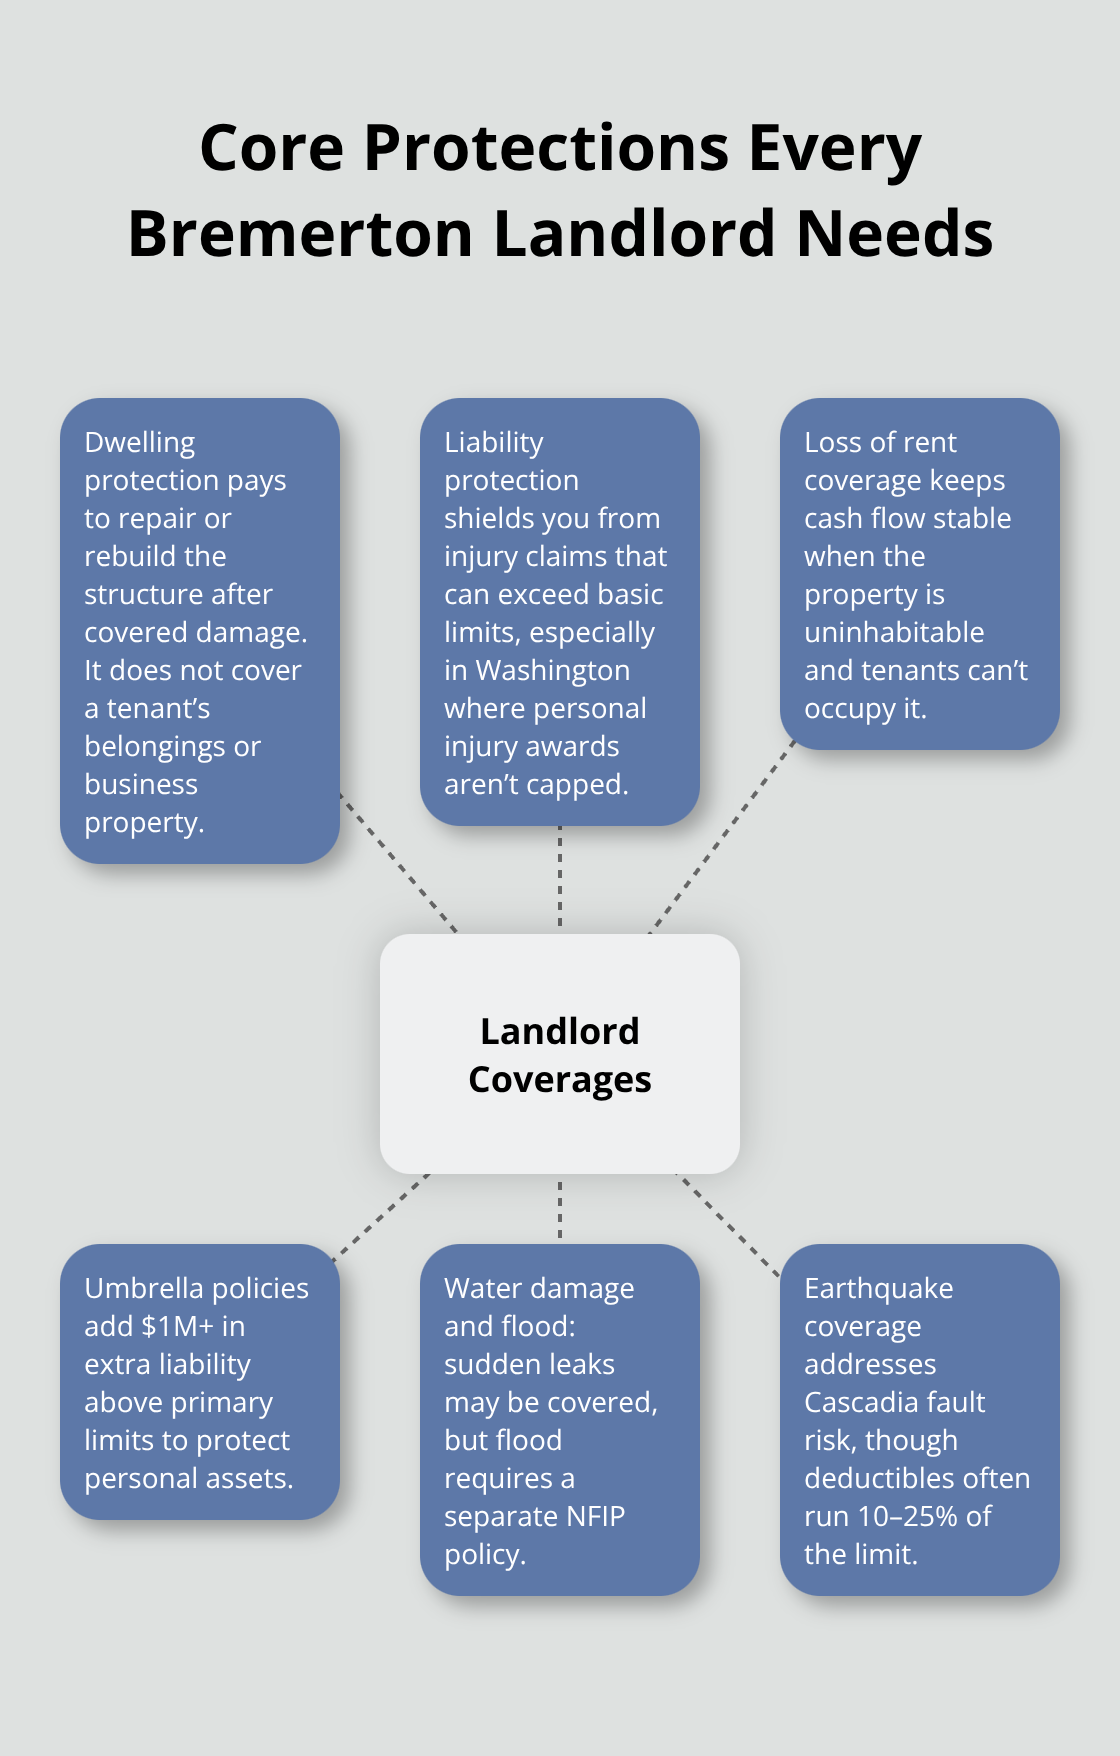
Landlord insurance covers the dwelling structure itself, liability protection if someone gets injured at your property, and loss of rent income when the property becomes uninhabitable. This coverage addresses the operational reality of renting property. If a tenant causes damage beyond normal wear and tear, landlord insurance covers repairs. If a guest slips and sues your tenant, your liability coverage protects you from that claim.
The loss of rent protection pays your mortgage and expenses while you repair damage and find new tenants, preventing the financial collapse that happens when income stops but bills continue. Bremerton landlords in the Puget Sound region face specific weather-related risks that standard homeowners policies either exclude or severely limit (flooding, wind damage, and seismic activity top that list). Landlord policies can be customized to include flood and earthquake coverage, which matter significantly for Washington properties.
Regional Risks Require Specialized Coverage
A single incident can wipe out months or years of rental income without the right protection in place. The Pacific Northwest’s climate and geology create exposures that generic homeowners policies simply don’t address. Customized landlord coverage prevents the scenario where weather or natural disaster destroys both your property and your cash flow simultaneously.
Key Coverage Types for Bremerton Rental Properties
Dwelling Protection Covers Your Building Structure
Dwelling protection forms the foundation of any landlord policy in Bremerton. This coverage pays to rebuild or repair the structure itself when damage occurs, whether from fire, weather, or vandalism. The critical detail most landlords miss: dwelling coverage applies only to the building structure, not your tenant’s belongings or business operations.
If a tenant causes $15,000 in damage to walls, flooring, or the roof, dwelling coverage handles the repairs. If that same tenant’s guest breaks a window and damages the tenant’s furniture, your policy doesn’t cover the furniture. Bremerton landlords should calculate dwelling coverage based on replacement cost, not market value. A property worth $400,000 to sell might cost $550,000 to rebuild from scratch due to labor and material costs in the Pacific Northwest. Underestimating this number creates a coverage shortfall that appears only when you file a claim. A professional replacement cost estimate protects you before you lock in coverage limits.
Liability Protection Shields You From Injury Claims
Liability protection separates financially stable landlords from those facing catastrophic losses. If a tenant’s guest slips on ice in your Bremerton rental’s parking lot and suffers a broken hip, they can sue you directly for medical bills, lost wages, and pain and suffering. A serious injury claim easily reaches $250,000 to $500,000, and standard liability limits of $100,000 or $300,000 disappear instantly.
Washington state doesn’t cap personal injury awards, meaning a jury could award significantly more than you anticipated. Your liability coverage protects your personal assets when claims exceed your policy limits. Without adequate liability protection, a single accident can force you to liquidate savings or sell property to cover a judgment.
Loss of Rent Coverage Protects Your Cash Flow
Loss of rent coverage protects your cash flow when the property becomes uninhabitable and tenants can’t occupy it. If a fire forces you to evacuate the building for three months of repairs, loss of rent coverage pays your mortgage, property taxes, insurance premiums, and utilities during that period. Most Bremerton landlords don’t realize their personal income depends entirely on this coverage working correctly.
Without it, you’re personally responsible for those expenses while receiving zero tenant income, creating a financial emergency that forces you to deplete savings or take on debt. Loss of rent typically covers 12 months of lost income, though you can adjust this based on local market conditions and your financial cushion. The next section examines additional coverages that address Bremerton’s specific environmental and weather-related risks.
Protecting Your Investment with Additional Coverages
Standard landlord insurance provides the foundation, but Bremerton’s specific risks demand additional layers of protection that most landlords overlook until a claim happens. Umbrella policies extend your liability coverage far beyond what a basic landlord policy provides, which matters enormously when a serious injury claim exhausts your standard limits. If someone suffers a permanent disability at your rental property and sues for $750,000, your $300,000 liability limit leaves you personally responsible for $450,000.
Umbrella Policies Extend Your Liability Protection
A umbrella policies starting at $1 million in additional coverage costs $383 annually for a person with one home, two cars, and two drivers-a modest expense that protects your entire net worth from a single incident. A judgment against you can follow you for years through wage garnishment or asset seizure, making additional liability protection essential for any landlord with multiple properties or significant personal assets. This additional layer sits above your standard landlord policy and activates only after your primary coverage limits are exhausted, providing the financial shield that separates manageable losses from catastrophic ones.
Water Damage Requires Aggressive Action in the Pacific Northwest
Water damage represents the single most common insurance claim in Washington state, yet most landlords treat it as an afterthought. The National Association of Insurance Commissioners reports that water damage claims account for approximately 29% of all homeowners insurance claims, and rental properties face even higher exposure due to tenant negligence and delayed maintenance reporting. A burst pipe in winter costs $10,000 to $25,000 in repairs, but you’re also losing rent for weeks while contractors work.
Standard landlord policies cover sudden water damage from burst pipes or roof leaks, but they explicitly exclude damage from poor maintenance, backed-up sewers, or gradual seepage. If a tenant fails to report a slow leak under the bathroom sink for three months and mold spreads through the subflooring, your claim gets denied because the damage resulted from negligence rather than a sudden event. Schedule annual plumbing inspections on your Bremerton rentals and document everything in writing, since insurers scrutinize water claims heavily. Separate flood insurance through the National Flood Insurance Program is non-negotiable if your property sits within a mapped flood zone-standard policies won’t touch flood damage, period.
Earthquake Coverage Protects Against Pacific Northwest Geology
The Cascadia Subduction Zone runs directly offshore from Bremerton, and the U.S. Geological Survey estimates a 14% probability of a magnitude 9.0 earthquake striking the Pacific Northwest within the next 50 years. That’s not theoretical risk-it’s geological reality that affects property values and insurance costs. A significant earthquake easily causes $50,000 to $200,000 in structural damage to rental properties, damage that standard policies exclude entirely.
Earthquake coverage adds $400 to $800 annually to your landlord policy depending on your building’s age and construction type, but it’s the only protection you have when the ground moves. Older concrete-block or unreinforced masonry buildings face substantially higher earthquake risk than newer wood-frame construction, so if your Bremerton rental uses older materials, earthquake coverage transitions from optional to essential. The deductible on earthquake policies typically runs 10% to 25% of your coverage limit, meaning you absorb significant out-of-pocket costs before insurance pays, so calculate this into your financial planning before a quake happens.
Final Thoughts
Bremerton rental property coverage protects your investment from the specific risks that standard homeowners policies ignore. Dwelling protection, liability coverage, and loss of rent protection form the foundation of any landlord policy, but the Pacific Northwest’s environmental hazards demand additional layers. Umbrella policies extend your liability shield beyond standard limits, water damage coverage addresses Washington’s most common claim type, and earthquake insurance protects against genuine geological risk from the Cascadia Subduction Zone.
The financial stakes are too high to guess about coverage. A single uninsured incident can eliminate years of rental income and force you to liquidate personal assets. Bremerton landlords who skip adequate protection learn this reality only after filing a claim and discovering their policy doesn’t apply.
We at H&K Insurance Agency work with landlords throughout the Puget Sound region to build customized coverage that matches your specific properties and risk profile. As an independent agency representing multiple carriers, we compare rates and structure packages that protect your investment without overpaying for unnecessary coverage. Contact H&K Insurance Agency to review your current coverage and identify gaps before they cost you money.
