Kitsap Auto Insurance Options: Choosing The Right Policy
Finding the right Kitsap auto insurance options can feel overwhelming when you’re comparing coverage types, rates, and discounts. At H&K Insurance Agency, we’ve helped countless drivers in our community navigate these decisions and find policies that actually fit their needs and budgets.
This guide walks you through the coverage types Washington requires, the factors that shape your premiums, and practical strategies to lower your costs without sacrificing protection.
Understanding Auto Insurance Coverage Types in Kitsap County
Washington State’s Minimum Liability Requirements
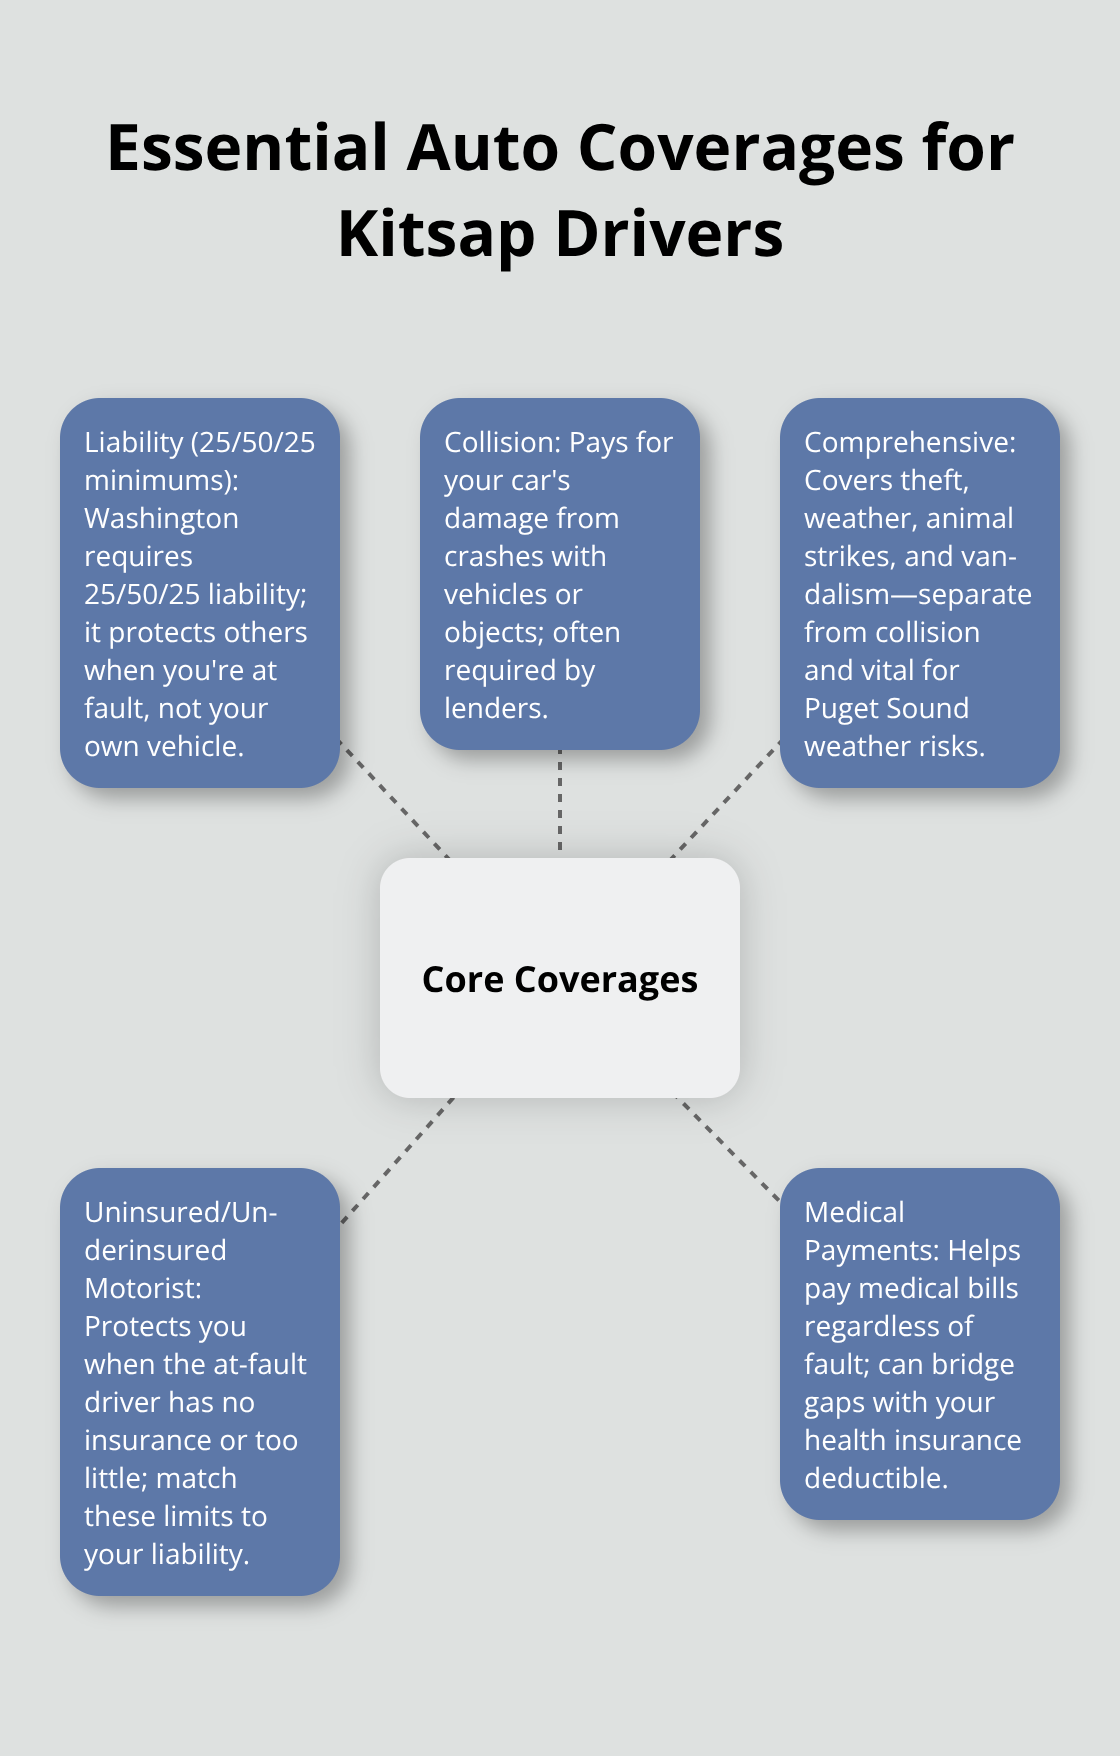
Washington State mandates that all drivers carry minimum liability coverage of 25/50/25, meaning $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage. This baseline protects the other party when you’re at fault in a crash-not your own vehicle or injuries. However, these minimums are dangerously low. The average cost of a serious injury claim in Washington exceeds $100,000, and a single at-fault accident can wipe out your personal assets if you lack adequate protection.
We recommend carrying at least 100/300/100 coverage, which costs only marginally more than the state minimum but provides substantially better protection. This higher limit makes financial sense for most Kitsap drivers, especially those with home equity or retirement savings worth protecting.
Collision and Comprehensive Coverage Explained
Collision and comprehensive coverage are optional but highly practical if you have a car loan or lease, since lenders require them. Collision pays for damage when you hit another vehicle or object, while comprehensive covers theft, weather, animal strikes, and vandalism-two separate protections that address different risks.
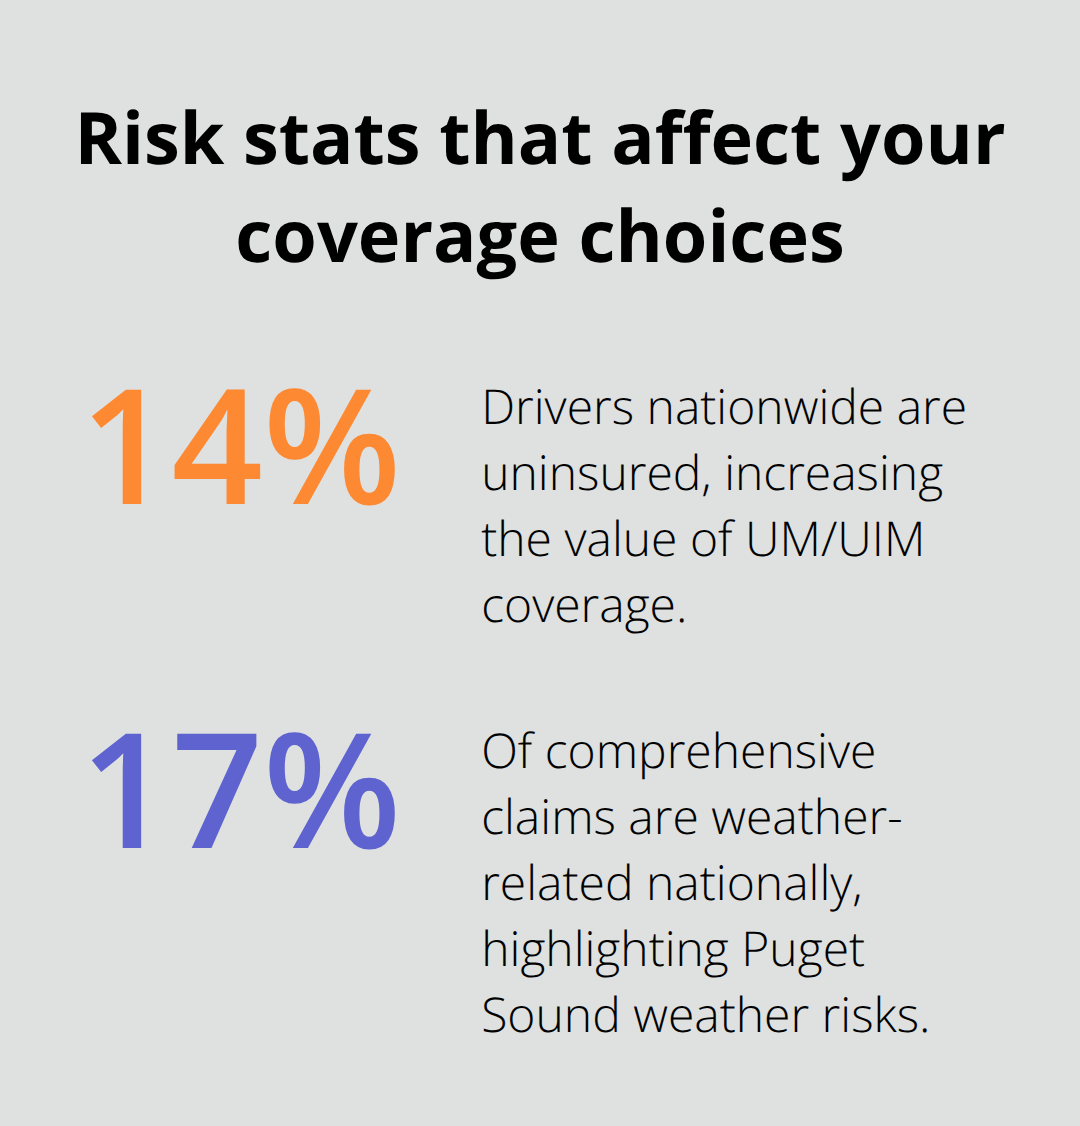
Kitsap County residents should seriously consider comprehensive coverage given our region’s weather patterns. Weather-related claims account for roughly 17% of all comprehensive claims nationally, and our Puget Sound winters bring heavy rain, occasional ice, and falling debris from older trees common in residential areas. This coverage protects your investment when nature strikes.
Uninsured and Underinsured Motorist Protection
Uninsured and underinsured motorist coverage is where many Kitsap drivers leave themselves exposed. Washington State does not require this coverage, yet roughly 14% of drivers nationwide carry no insurance at all. If an uninsured driver hits you, your liability coverage won’t help-it only covers the other party.
Uninsured motorist coverage protects you and your passengers from medical bills and lost wages when hit by someone without insurance. Underinsured motorist coverage kicks in when the at-fault driver’s liability limits fall short of your damages. We recommend carrying uninsured and underinsured motorist coverage at the same limits as your liability protection, making it a unified safety net.
Medical Payments Coverage and Additional Protections
Many Kitsap drivers also overlook medical payments coverage, which pays up to a chosen limit for medical expenses regardless of fault. This coverage reduces your out-of-pocket costs and avoids gaps between your auto insurance and health insurance deductibles.
The practical reality is that Washington’s minimum requirements leave you financially vulnerable. Your coverage levels should reflect your assets, vehicle value, and driving patterns rather than simply meeting the legal floor. Once you understand what protection you need, the next step involves recognizing how your personal situation affects what you’ll actually pay for that coverage.
Factors That Affect Your Auto Insurance Rates
How Your Driving Record Impacts Premiums
Your driving record stands as the single most powerful factor determining what you’ll pay for auto insurance, and the impact is brutal. A DUI conviction hits hard, typically raising rates by 60% to 100% for up to ten years. Insurers track every claim and violation, and Kitsap County drivers with clean records pay substantially less than those with accidents or tickets.
If you’ve had violations, time and a clean driving record going forward represent your only real solutions. One minor speeding ticket might add 10% to your annual premium, but that cost compounds year after year if additional violations follow. The financial damage accumulates quickly when multiple infractions appear on your record.
Vehicle Type and Age Considerations
Your vehicle itself matters more than most drivers realize. A 2024 Honda Civic costs significantly less to insure than a 2024 Dodge Charger because repair costs, theft rates, and safety ratings differ dramatically. The Highway Loss Data Institute tracks which vehicles cost insurers the most to repair and replace, and sports cars consistently rank at the top.
Older vehicles often cost less to insure simply because their actual cash value is lower, even though comprehensive and collision deductibles might make that savings misleading. A 2010 vehicle worth $8,000 might have lower premiums than a 2023 vehicle worth $28,000, but a $1,000 deductible still stings the same way. Your choice of vehicle directly shapes your insurance bill for years to come.
Location and Commute Patterns in the Puget Sound Region
Location and commute patterns in the Puget Sound region create measurable differences in what drivers pay. Kitsap County drivers who commute through Seattle experience higher rates than those with short local drives, because higher-traffic areas generate more accidents. A driver commuting from Bremerton to downtown Seattle daily faces different risk than someone working locally, and insurers price that accordingly.
Weather also influences rates-our region’s frequent rain and occasional ice mean more weather-related claims, which spreads costs across all drivers in the area. Even your zip code matters; densely populated areas around Port Orchard and Bremerton typically cost more to insure than rural Kitsap neighborhoods due to theft and accident frequency. These location-based factors remain largely outside your control, but understanding them helps explain your quote. Once you know what drives your rates, you can focus on the strategies that actually lower your costs without sacrificing the protection you need.
How to Compare and Select the Best Auto Insurance Policy
Bundling Strategies to Lower Your Overall Costs
Comparing auto insurance quotes without a strategy wastes time and leaves money on the table. The real path to lower rates involves three concrete actions: bundling your policies strategically, identifying every discount you qualify for, and working with an agent who understands Kitsap’s specific insurance landscape. Most drivers accept their first quote and never look deeper, which means they overpay year after year.
You can save up to 17% on average by combining auto and home insurance together. That’s not theoretical savings-it’s money that stays in your account instead of going to an insurance company. When you combine auto, home, and potentially boat or RV coverage under one policy, insurers reward you with substantial discounts because they reduce their administrative costs and customer acquisition expenses.
Discount Opportunities Available to Kitsap Residents
Discount opportunities specific to Kitsap residents go far deeper than most drivers realize. Good driver discounts typically range from 10% to 25%, but you only receive them if you actively request them and maintain a clean record going forward. Safety feature discounts for vehicles equipped with anti-theft devices, automatic braking, or lane departure warnings save another 5% to 15% depending on your insurer.
Completion of defensive driving courses through organizations like the American Automobile Association qualifies you for additional reductions that typically last three to five years. Some insurers offer usage-based programs that monitor your actual driving habits through a mobile app, potentially saving safe drivers up to 30% based on real data rather than assumptions. Student discounts for drivers maintaining a B average, good student discounts, and paid-in-full discounts for annual premiums all add up quickly when combined.
Working with a Local Independent Agent for Personalized Quotes
The challenge is knowing which discounts apply to your situation and which insurers offer them, because eligibility varies dramatically across carriers. A local independent agent who represents multiple top carriers gives you access to all available discounts without the frustration of contacting fifteen different companies yourself. An independent agent compares your specific situation across different insurers, identifies which discounts you qualify for, and structures your policies to maximize savings.
This approach takes hours off your research time and consistently produces lower quotes than shopping online alone, particularly for Kitsap drivers with unique situations (military service, multiple vehicles, or specialized coverage needs like classic car insurance or RV protection). An independent agent working in the Kitsap area understands local risk factors, weather patterns, and commute realities that shape your actual insurance needs. That local expertise translates directly into better coverage recommendations and lower premiums than national online platforms can offer.
Final Thoughts
Finding the right Kitsap auto insurance options requires you to understand what coverage you actually need, recognize the factors that shape your premiums, and take concrete action to lower your costs. Washington’s minimum liability requirements leave most drivers dangerously exposed, which is why we recommend carrying higher limits that match your assets and financial situation. Your driving record, vehicle type, and location all influence what you’ll pay, but these factors become manageable once you know how to work with them strategically.
Shopping alone across multiple insurance companies wastes hours and produces incomplete results because you’ll miss discounts and coverage combinations that lower your actual costs. An independent agent compares your situation across top carriers, structures your policies to maximize savings, and ensures you’re not overpaying for protection you don’t need or underpaying for gaps that could devastate your finances. Bundling your auto insurance with home, boat, or RV coverage captures savings that typically reach 17% or more, while identifying every discount you qualify for (from good driver reductions to safety feature credits) compounds those savings further.
We at H&K Insurance Agency serve the Kitsap community with personalized insurance solutions tailored to your actual needs. Contact H&K Insurance Agency to get personalized quotes and see how much you can save on your auto insurance coverage.
